Philadelphia’s 2026 Gold Rush: Why the World Cup and MLB All-Star Game are Changing the Multi-Family Game

If you’re considering jumping into the Philadelphia real estate market, you couldn't have picked a more electric time. Welcome to the 2026 Gold Rush. Right now, as we sit in March of 2026, the city isn't just buzzing: it’s vibrating. With the FIFA World Cup and the MLB All-Star Game both descending on the City of Brotherly Love this year, we are witnessing a fundamental shift in how multi-family and short-term rental properties are valued.

At Emerald Capital Funding, we’ve been watching the data crawl upward for months, and the reality is hitting: Philadelphia is officially under-housed for the massive influx of humanity headed our way. If you’re an investor looking to capitalize on this once-in-a-generation surge, this guide will equip you with the insights and financing strategies you need to win the deal before the first whistle blows.

The Math Behind the Madness: $770 Million and a Massive Bed Shortage

Let’s talk numbers, because that’s where the opportunity lives. Research shows that the combined impact of the World Cup and the MLB All-Star Game is projected to pump a staggering $770 million into the local economy. We’re talking about 500,000 visitors for the World Cup matches and another 50,000 for the All-Star festivities.

Here is the problem (and your opportunity): Philadelphia only has about 14,400 hotel rooms. Even with every hotel at 100% capacity, there is a massive deficit. We are looking at a demand for over 56,000 room nights that the traditional hospitality industry simply cannot handle.

This means two things for real estate investors:

  1. Short-Term Rental (STR) Goldmine: Residential properties are being converted at record speeds to handle the overflow.
  2. Multi-Family Dominance: Investors are snapping up 5+ unit buildings to provide corporate housing and mid-term rentals for the support staff, media, and security teams that accompany these global events.
Historic Philadelphia rowhomes showcasing multi-family investment opportunities for the 2026 World Cup.

Why Multi-Family 5-Units are the Sharpest Play Right Now

If you've been sticking to single-family rentals, 2026 is the year to think bigger. When you cross the line into commercial multi-family (5 units or more), the valuation game changes. It’s no longer just about "comps" in the neighborhood; it’s about the Net Operating Income (NOI) your building generates.

With the current rental spikes driven by global sporting events, your NOI is likely to look better than ever. However, traditional banks are often too slow to move on these deals. That’s where we come in. Whether you are looking at a stabilized asset or a value-add project, understanding multifamily DSCR loans is essential. These loans focus on the property’s ability to cover its own debt, allowing you to scale faster than you ever could with a standard mortgage.

Actionable Takeaway: Look for "distressed" multi-family units in West Philly or near the Sports Complex in South Philly. Use a bridge loan to acquire and renovate quickly, then cash out into a long-term rental loan once the units are stabilized.

Geographic Hotspots: Where the Crowds (and Cash) are Heading

You don't need a stadium-view property to win this year, though it certainly wouldn't hurt. Because of the hotel shortage, the "spillover effect" is real.

  • South Philadelphia: Obviously, proximity to the Lincoln Financial Field and Citizens Bank Park is king. If you can find a rowhome or small multi-family within walking distance, you’re looking at premium rental rates.
  • The "Collar Counties": Don't sleep on Delaware County (Delco) or Montgomery County. With the city center booked solid, visitors are looking for easy access via SEPTA. Properties near Regional Rail lines are seeing a significant uptick in demand.
  • Fishtown and Northern Liberties: These remains the go-to for the younger, high-spending demographic coming for the All-Star Game.
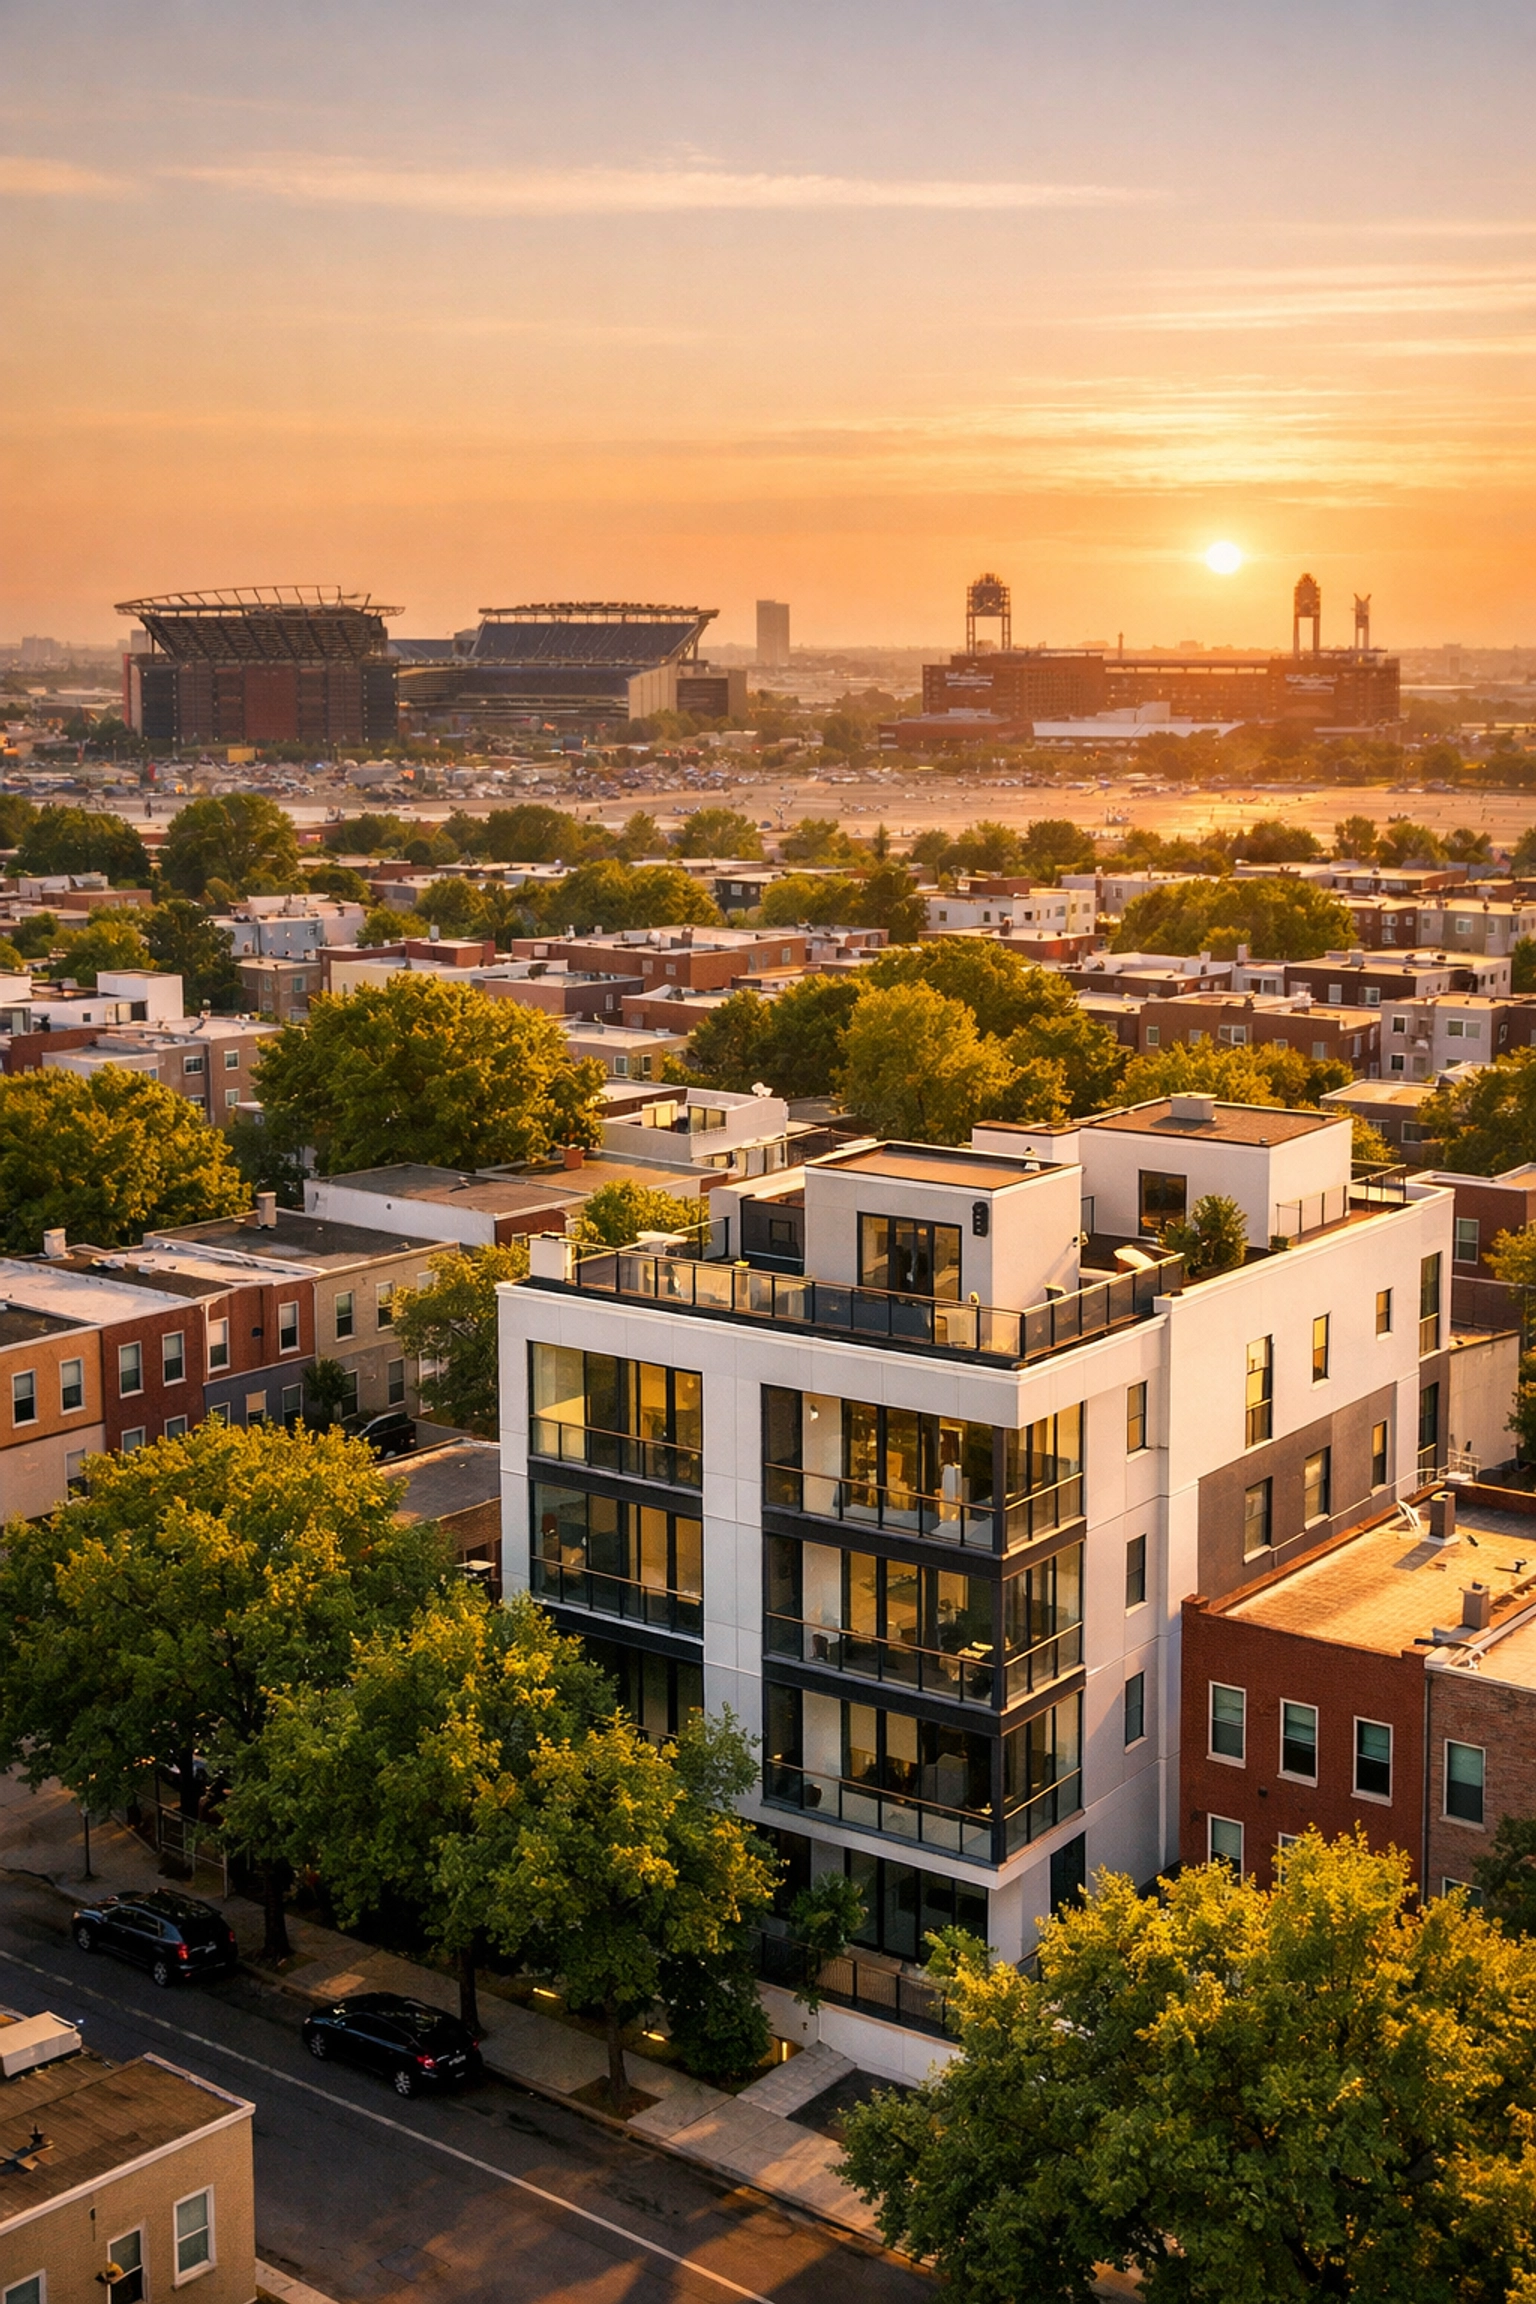
Modern multi-family housing in Philadelphia near the stadium complex, a prime target for real estate lending.

Financing Your Move: Bridge vs. DSCR

Speed is your greatest weapon in a hot market. In Philly right now, if you find a deal, you have about 48 hours before five other investors are sniffing around it. This is why you need a lender who speaks your language.

The Bridge Loan: Your "Speed to Lead" Tool

If you find a property that needs a little love before it’s ready for World Cup fans, a bridge loan is your best friend. It allows you to close fast: often in as little as 5–7 days: and covers the cost of the acquisition and the renovations. At Emerald Capital Funding, we’ve simplified bridge loans so you can focus on the construction while we handle the heavy lifting of the capital.

The DSCR Loan: The Long-Term Wealth Builder

Once the property is renovated and the tenants (or short-term guests) are in place, you want to move that high-interest short-term debt into something more permanent. That’s where the Debt Service Coverage Ratio (DSCR) loan comes in. This is the toolbox essential for serious investors. We don't care about your tax returns or your DTI; we care about the property's income.

Pro Tip: If the property can cover the mortgage with its rental income, you’re in the clear. In a high-demand year like 2026, hitting those ratios is easier than ever.

The 90-Day "All-Star" Strategy

With the summer events fast approaching, you still have time to execute a "Micro-BRRRR." Here’s how successful investors are playing it right now:

  1. Acquire: Use a hard money or bridge loan to buy a 3-to-5 unit building in a transit-accessible neighborhood.
  2. Renovate: Focus on "hospitality grade" finishes: clean lines, smart locks, and high-speed Wi-Fi.
  3. Rent: List the units for the summer peak.
  4. Refinance: Use the massive rental income documented during the peak months to qualify for a high-LTV DSCR refi.
Renovated Philadelphia apartment interior highlighting the high-quality finish of a DSCR loan project.

Common Investor Questions (Q&A)

Q: Is it too late to buy for the 2026 events?
A: Not at all! While the "prime" deals are moving fast, the overflow demand will affect the entire region through the end of the year. Using a fast-closing bridge loan can still get you in a property and renovated before the peak of the World Cup matches.

Q: How do DSCR loans handle short-term rental income?
A: We love STRs! We often use AirDNA data or a 12-month history to project the income. In a market like Philly 2026, those numbers are very favorable for investors. You can check out more on how we view these in our DSCR loans explained section.

Q: What happens to the market after the games are over?
A: Great question. Philadelphia isn't just building for a two-week party. The infrastructure projects, transport upgrades, and the "spotlight effect" on the city create long-term value. You aren't just buying for a sports event; you're buying into a modernized urban center.

Don't Get Left on the Sidelines

The 2026 Philadelphia market is a high-stakes game, but with the right financing partner, the path to success is within your reach. Whether you’re looking to flip a rowhome in Delco or scale a multi-family portfolio in the heart of the city, we’ve got you covered.

At Emerald Capital Funding, we specialize in getting investors the capital they need when traditional banks say "wait." We don't do "wait." We do deals.

Ready to capitalize on the 2026 Gold Rush?

  • Apply Now to get pre-approved for your next Philly deal.
  • Contact Us to discuss your specific multi-family project.
  • Explore our Services to see which loan product fits your strategy.

Don't let the biggest year in Philadelphia real estate history pass you by. Let's get to work and make 2026 your most profitable year yet.

Trading Metal for Bricks: Why Savvy Investors are Selling Auto Loan Portfolios to Scale Multi-Family

If you’re considering a major shift in your investment strategy to capitalize on the 2026 market, welcome to the world of high-leverage real estate. For years, many institutional and private investors have found steady returns in the automotive sector. However, the landscape is changing. As we navigate the current economic climate, the most successful players are no longer content with holding "metal": depreciating assets tied to auto loans. Instead, they are looking toward "bricks": multi-family real estate assets that offer appreciation, tax advantages, and long-term stability.

In this guide, we’ll explore why selling auto loan portfolio assets is becoming a go-to move for investors looking to scale their wealth through real estate. Whether you are holding a small pool of paper or a massive institutional portfolio, this guide will equip you with the knowledge to transition your capital into the high-growth world of multi-family lending.

The Problem with "Metal": Why Auto Portfolios Are Losing Their Luster

Before we dive into the benefits of real estate, it’s important to understand the inherent risks of staying too long in the auto lending space. When you hold an auto loan portfolio, you are essentially betting on a depreciating asset.
As of March 2026, several factors are making auto loans a riskier bet:

  • Rapid Depreciation: Unlike real estate, a vehicle loses a significant portion of its value the moment it is driven off the lot. If a borrower defaults, the collateral is often worth far less than the remaining loan balance.
  • Operational Headaches: Managing an auto portfolio requires significant overhead: collections, repossessions, and dealing with physical collateral that can be hidden or damaged.
  • Inflationary Pressures: In 2026, the cost of vehicle maintenance and insurance has skyrocketed, putting additional strain on borrowers and increasing default rates across the board.

By selling auto loan portfolio assets now, you can lock in your gains and exit a market that is increasingly volatile. We’ve got you covered if the idea of liquidating feels daunting; the goal is simply to trade a shrinking asset for one that grows.

Comparing car keys to a multi-family property model to represent selling auto loan portfolio assets.

The Magic of "Bricks": Why Multi-Family is the Ultimate Scale Play

If auto loans are about short-term cash flow with high risk, multi-family real estate is about long-term wealth creation. When you move your capital into "bricks," you are moving into an asset class that people literally cannot live without.

Here is why savvy investors are making the switch:

  1. Appreciation and Equity: While cars lose value, well-managed multi-family properties generally appreciate over time. You aren't just earning interest; you are building equity in a physical asset that grows in value.
  2. Tax Benefits: Real estate offers powerful tax incentives, including depreciation and 1031 exchanges, which are largely unavailable in the auto lending world.
  3. Scalability: It is much easier to scale a portfolio from 10 units to 100 units than it is to manage thousands of individual car loans.
  4. Hedge Against Inflation: Rents typically rise with inflation, ensuring that your income stream keeps pace with the cost of living: something fixed-rate auto paper simply can't do.

At Emerald Capital Funding, we specialize in helping investors leverage their capital to secure the best possible terms on multi-family deals. You can learn more about our approach on our about page.

The Strategy: How Selling Auto Loan Portfolio Assets Fuels Real Estate Growth

You might be wondering, "How do I actually make the transition?" The process is more systematic than you might think. It involves liquidating your current "paper" (the auto loans) to generate a massive injection of liquidity, which then serves as the down payment for high-leverage real estate.

Step 1: Portfolio Valuation

The first step is getting a clear picture of what your auto loan portfolio is worth in the secondary market. Buyers are looking for seasoned accounts with clean payment histories.

Step 2: Finding a Buyer

There are still institutional players and hedge funds looking for the yield that auto loans provide. By selling auto loan portfolio assets to these entities, you can exit the sector with a lump sum of cash.

Step 3: Deployment into Multi-Family

Once you have the liquidity, the real fun begins. With the right lending partner, $1 million in liquidated auto paper doesn't just buy $1 million in real estate: it can potentially control $4 million or $5 million in property through high-leverage financing.

With that said, the timing is crucial. The real estate market moves fast, and having your capital ready to go is the difference between winning a bid and losing out to a competitor.

Close-up of building a multi-family property model representing capital growth and real estate scaling.

Comparing the Numbers: Metal vs. Bricks

To truly see the value of this trade, let’s look at a hypothetical comparison over a 5-year period.

Feature Auto Loan Portfolio (Metal) Multi-Family Property (Bricks)
Asset Value Depreciates (Down 15-20% annually) Appreciates (Up 3-7% annually)
Cash Flow High interest, but finite term Monthly rent, potentially infinite
Tax Impact Interest income is fully taxable Significant offsets via depreciation
Collateral Mobile, high-risk, depreciating Fixed, low-risk, appreciating
Leverage Potential Difficult to re-leverage High (75-80% LTV common)

As you can see, the "bricks" strategy is built for those who want to achieve their financial goals with more security and less daily management. Success is within your reach when you stop chasing high-risk yield and start building a foundation of real property.

Common Questions About Making the Switch

Q: Is selling auto loan portfolio assets a complicated process?
A: It can be, but with the right broker or secondary market platform, you can liquidate relatively quickly. The key is having your data organized and your payment histories verified.

Q: Won't I lose out on the high interest rates car loans provide?
A: While car loans may have a higher nominal interest rate, the "net" return is often lower once you factor in depreciation of the collateral and the cost of defaults. Real estate offers a total return (cash flow + appreciation + tax savings) that usually outperforms auto paper in the long run.

Q: What kind of leverage can I get on multi-family properties?
A: Depending on the property and your experience, you can often find leverage between 70% and 80%. This means your liquidated cash goes much further. Check out our services page for more details on what we offer.

Q: Does Emerald Capital Funding help with the liquidation of auto loans?
A: While we focus on the real estate lending side, we are the bridge that helps you deploy that capital once you’ve liquidated. We provide the "bricks" to replace your "metal."

A professional architectural view of a multi-family building representing a solid real estate investment.

Actionable Takeaways for the Savvy Investor

If you are ready to stop managing a fleet and start managing an empire, here are your next steps:

  • Audit Your Portfolio: Determine the current "Blue Book" value of the collateral in your auto portfolio and calculate your actual net yield after defaults.
  • Research Multi-Family Markets: Look for areas with high occupancy rates and strong rental growth. You can see where we currently lend by visiting our geographic coverage page.
  • Get Pre-Qualified: Don't wait until you've sold your portfolio to talk to a lender. Knowing your buying power ahead of time allows you to move with confidence.
  • Execute the Sale: Partner with a secondary market specialist to begin selling auto loan portfolio tranches.

Your Pathway to Financial Security

Trading metal for bricks isn't just a trend; it's a fundamental shift toward more stable, scalable wealth. The headaches of repossessions and depreciating assets can be a thing of the past. By moving into the multi-family space, you are securing a future built on tangible assets that provide shelter and value for decades to come.

Don't worry if you've never done a large-scale real estate deal before: with the right approach and a professional team behind you, the transition is smoother than you might expect. We are here to help you navigate every step of the lending process.

Are you ready to turn your paper into property?

At Emerald Capital Funding, we specialize in providing the high-leverage solutions you need to scale your real estate portfolio. Whether you are looking for bridge loans or permanent multi-family financing, our team is ready to help you close your next big deal.

Apply Now to start your journey into multi-family investing.

If you have more questions or want to discuss your specific strategy, feel free to contact us today. Let's build something lasting together.

The Anti-Bank Manifesto: Why Private Money is Your Only Real Move in 2026

If you’re considering scaling your real estate portfolio in 2026, you’ve likely noticed a chilling trend: the local bank branch that used to be your best friend is suddenly acting like a disinterested ex. Welcome to the era of the "Bank Ghosting," where traditional institutions have wrapped themselves in so much red tape and regulatory caution that they’ve become virtually useless for the modern, fast-moving real estate investor.

At Emerald Capital Funding, we’ve seen the shift firsthand. While federal regulators are busy trying to force banks to be more inclusive, the reality on the ground is that banks are moving slower than ever. If you want to actually close deals this year, this guide will equip you with the mindset shift you need to stop begging for bank approvals and start leveraging private money as your primary financial weapon.

The Great Bank Ghosting: Why Traditional Lenders are Failing You

We’ve all been there. You find a perfect multi-family property or a distressed flip with massive upside. You submit your paperwork to a traditional lender, and then… silence. Or worse, a request for a document that doesn’t exist, followed by a three-week wait for an "underwriting committee" that only meets on the second Tuesday of a blue moon.

In 2026, traditional banks are bogged down by:

  • Excessive Regulatory Fear: Even with new mandates to prevent "debanking," banks are terrified of risk. Their response is to over-scrutinize every penny, turning a simple loan application into a forensic audit.
  • The "Box" Mentality: If your deal doesn't fit into a very narrow, pre-defined box (perfect credit, massive cash reserves, and a property that’s already pristine), you’re out.
  • Glacial Timelines: A 45-to-60-day closing window is standard for banks. In today’s competitive market, that’s not just slow, it’s a deal-killer.

With that said, the savvy investor knows that waiting on a bank is a choice, not a necessity. By pivoting to private money, you’re not just finding a "backup plan", you’re upgrading your entire acquisition strategy.

A stopwatch on architectural blueprints highlighting fast real estate deal closing with private money.

Speed: The Only Currency That Matters in a Competitive Market

In the current real estate landscape, speed is your greatest competitive advantage. Sellers are tired of deals falling through because a buyer’s bank pulled the rug out at the eleventh hour. When you walk into a negotiation with the backing of private capital, you are effectively a cash buyer.

Before we dive into the mechanics, let’s look at the numbers. While a bank might take two months to fund a loan, a private lender like Emerald Capital Funding can often get you to the closing table in a fraction of that time.

The Private Money Advantage:

  1. Direct Communication: You talk to decision-makers, not "loan officers" who have to check with a regional manager.
  2. Asset-Based Underwriting: We care more about the value and potential of the property than your personal debt-to-income ratio.
  3. Simplified Paperwork: We focus on what matters: the deal's viability and your exit strategy.

If you’re ready to see how fast you can move, you can apply now and experience the difference between a bureaucratic hurdle and a financial partnership.

Flexibility Over Formulas: Looking at the Deal, Not Just the FICO

Traditional banks are obsessed with your past. They look at your tax returns from three years ago and your credit score from last month. But as a real estate investor, you’re focused on the future, the value you’re going to create in a property.

Private money allows for the kind of flexibility that banks simply can’t match. This is especially true for specialized products like DSCR loans (Debt Service Coverage Ratio), where the loan is qualified based on the property’s rental income rather than your personal paycheck.

Why Flexibility Wins:

  • Property Condition: Banks won't touch a "distressed" property. Private lenders love them because we understand fix-flip loan basics and the value of a solid renovation plan.
  • Creative Structuring: Need a bridge loan to cover a gap? Or a cross-collateralized deal? Try asking a traditional bank for that, and they’ll look at you like you’re speaking a foreign language.
  • Investor Mindset: We speak your language. We understand that a temporary dip in cash flow during a renovation is part of the process, not a reason to deny a loan.

Actionable Takeaway:

Stop trying to fix your "bankability" and start focusing on your "deal-ability." If the numbers on the property work, private money will be there to back you.

Keys to a multi-family property held after closing a deal with flexible private money lending.

The ROI of "Expensive" Money: Doing the Math

The biggest pushback we hear about private money is the cost. "But Bill," investors say, "the interest rate is higher than the bank!"

Yes, it is. But let’s do some blunt math. What is the interest rate on a deal that never closes? What is the cost of the three deals you missed while waiting 60 days for a bank to tell you "no"?

In 2026, successful investors view interest rates as a line-item expense, not a barrier to entry. If a private loan costs you 2% more in interest but allows you to capture a deal with $100,000 in equity, that interest is the best investment you’ll ever make.

Consider these factors:

  • Opportunity Cost: Every day your capital is sitting on the sidelines is a day it’s not growing.
  • Negotiating Power: Being able to close in 10 days often allows you to negotiate a lower purchase price from a motivated seller, often offsetting the cost of the loan entirely.
  • Scale: Private money allows you to move onto the next deal faster, increasing your annual velocity and total profit.

A modern glass house with a green foundation symbolizing growth and stable real estate financing.

Q&A: Your Private Money Questions Answered

We know that switching from traditional banking to private lending can feel like a big move. Here are the most common questions we get from investors looking to make the leap:

Q: Is private money only for people with bad credit?
A: Absolutely not. Many of our most successful clients have 800+ credit scores. They use private money because of the speed and the ability to scale beyond what a traditional bank’s "maximum door limit" allows.

Q: What types of properties do you lend on?
A: We focus on non-owner occupied residential (1-4 units), multi-family, and commercial projects. You can see more about our specific services to see if your deal fits.

Q: Do I need a lot of experience to get a private loan?
A: While experience helps, it’s not always a requirement. We love working with seasoned pros, but we also provide the capital for newcomers who have a solid property and a clear plan. Don't worry, we’ve got you covered with the resources to help you understand the process.

Q: How much of a down payment do I need?
A: This varies by deal, but generally, private lenders look for "skin in the game." However, because we focus on the After Repair Value (ARV) for many loans, your out-of-pocket costs can often be lower than a traditional 20% down bank loan.

Final Thoughts: The Pathway to Financial Security in 2026

The "Anti-Bank Manifesto" isn't about hating banks; it’s about recognizing that they are no longer the right tool for the job. In a high-speed, high-stakes real estate market, you need a financial partner that moves at the speed of business, not the speed of bureaucracy.

Success is within your reach, but it requires the right weapons. By choosing private money, you’re choosing to take control of your timeline, your deals, and your future. Don’t let a "no" from a bank officer who doesn't understand your vision stop you from achieving your financial goals.

Ready to stop waiting and start closing?

At Emerald Capital Funding, we’re ready to help you execute your 2026 strategy with precision and speed. Whether you're looking for a quick fix-and-flip or a long-term rental hold, our team is standing by to turn your vision into a reality.

  • Step 1: Review your current deal's numbers.
  • Step 2: Contact us to discuss your scenario.
  • Step 3: Apply now and get your deal moving.

The banks might be ghosting you, but we’re picking up the phone. Let’s get to work.

Beyond Single Family: Why 2026 is the Year to Pivot into 5-10 Unit Properties

If you’re considering how to take your real estate portfolio from "side hustle" to "empire status" in 2026, you’ve likely hit a familiar wall. You’ve mastered the single-family rental, maybe you’ve even juggled a few duplexes or four-plexes. But as you look at the market landscape this year, the competition for residential inventory is fiercer than ever, and the scaling process feels slow.

Welcome to the world of small-balance commercial real estate.

Specifically, we’re talking about the 5-10 unit sweet spot. In the lending world, once you hit that fifth unit, the rules change. You cross the line from residential lending into commercial loans, and while that might sound intimidating, it is actually the secret doorway to rapid growth. At Emerald Capital Funding, we’ve spent years helping investors bridge this gap, and we’re here to tell you: 2026 is the absolute best time to make the jump.

Why the "Residential Ceiling" is Holding You Back

Most investors start with 1-4 unit properties because they are familiar. They use the same appraisal methods as the house you live in, and the financing feels "normal." However, residential investing has a ceiling. When you buy a single-family home, its value is dictated by what the neighbor’s house sold for. You can renovate it to the nines, but if the neighborhood cap is $400,000, that’s your limit.

When you pivot to multi family 5 units or more, you break through that ceiling. You are no longer just buying a building; you are buying a business. In the commercial world, value is driven by income, not just comparable sales. This shift in perspective is the first step toward achieving your financial goals with much more control over your destiny.

Modern 8-unit multi-family property representing a pivot from single-family to commercial real estate investment.

The Commercial Advantage: Valuation Based on Performance

The biggest "aha!" moment for investors moving into the 5-10 unit space is understanding Net Operating Income (NOI). In a residential deal (1-4 units), the lender looks at your personal income and the house's "comps." In a commercial deal, we look at the property’s ability to generate cash.

  1. Forced Appreciation: Because value is tied to income, every dollar you save in expenses or gain in rent increases the property's value exponentially. If you increase the annual NOI of a 10-unit building by $10,000 in a market with a 6% cap rate, you’ve just added over $166,000 to the property’s value.
  2. Economies of Scale: Think about the logistics. Replacing one roof on a 10-unit building is significantly cheaper per unit than replacing 10 separate roofs on 10 single-family houses. You have one tax bill, one insurance policy, and one lawn to mow.
  3. Vacancy Protection: If your single-family rental goes vacant, you are 100% vacant. If one tenant leaves your 8-unit building, you are still 87.5% occupied. Your cash flow remains stable while you find a new tenant.

If you want to understand how this math works in real-time, check out our guide on multifamily DSCR loans for 5+ units to see how the underwriting shift benefits your bottom line.

Why 2026 is the Pivot Point

Market data for 2026 shows a unique "Goldilocks" zone for the 5-10 unit asset class. We are seeing a recovery in multifamily fundamentals where rent growth is stabilizing and the massive oversupply of "mega-complexes" from previous years is being absorbed.

While institutional capital is often chasing 100-unit buildings, and "mom-and-pop" investors are fighting over single-family homes, the 5-10 unit space is often overlooked. It’s too big for the average beginner and too small for the giant hedge funds. This creates a massive opportunity for savvy investors to swoop in and pick up high-performing assets with less competition.

Furthermore, with the current stability in the 2026 lending environment, commercial loans for these mid-range properties have become more accessible. At Emerald Capital Funding, we’ve tailored our programs to support this specific transition, providing the leverage you need to scale without the red tape of a traditional big-box bank.

Financing the Move: How Emerald Capital Funding Simplifies the Process

Don't worry if you've never done a commercial deal before; we’ve got you covered. The transition from residential to commercial financing is actually simpler than many realize because the property does the heavy lifting.

When you apply for a loan on a 6-unit apartment building, we aren't obsessing over your DTI (Debt-to-Income ratio) or your tax returns from three years ago. We are looking at the DSCR (Debt Service Coverage Ratio). Essentially, does the property’s income cover the mortgage payments and expenses? If the numbers work, the deal works.

This guide will equip you with the knowledge that your personal "W-2 income" isn't the gatekeeper to wealth anymore. You can learn more about how this works in our deep dive on DSCR qualification truth.

House keys and a growth chart on a tablet, symbolizing successful commercial loan closing for real estate investors.

Actionable Steps to Pivot into 5-10 Unit Properties

Ready to make the move? Follow this systematic approach to secure your first commercial asset this year:

  • Audit Your Current Portfolio: Look at your 1-4 unit properties. Is there equity you can tap into? Sometimes selling two single-family homes or doing a cash-out refi can provide the down payment for an 8-unit building that doubles your cash flow.
  • Build Your "Commercial" Team: You’ll need a commercial-focused broker and a lender who understands the 5+ unit space. Traditional residential lenders often can't cross that "5-unit line," but we specialize in it.
  • Analyze the "Value-Add": Look for properties with "lazy" management, units with under-market rents or high utility costs that can be billed back to tenants. This is where you find the most significant upside.
  • Get a Pre-Approval Strategy: Before you start touring 10-unit complexes, talk to us. We can help you understand the LTC and LTV math that experts use to fund these deals.

Common Questions About 5-10 Unit Investing

Q: Do I need a different type of insurance for a 5+ unit building?
A: Yes. Once you hit 5 units, you move into a commercial insurance policy. While the cost is higher in total, the cost per unit is almost always lower than residential policies.

Q: Can I still use a DSCR loan for a 10-unit building?
A: Absolutely. In fact, DSCR loans are one of the most popular ways to fund these assets because they prioritize the property's performance over your personal financial history.

Q: Is the down payment higher for commercial loans?
A: Generally, you’re looking at 20-25% down. However, because the income is higher and the valuation is more predictable, many investors find that the return on equity is far superior to residential deals.

Q: What if the property needs work?
A: We offer specialized bridge loans that allow you to purchase a distressed 5-10 unit property, renovate it, and then stabilize it before moving into a long-term commercial loan. You can read more about bridge loans simplified to see if this fits your strategy.

A stabilized 10-unit multi-family residential complex showcasing the potential of commercial asset management.

Your Pathway to Financial Security

The jump from 4 units to 5 units is more than just adding one more door; it’s a shift in your entire investment philosophy. It’s moving from being a "landlord" to being a "real estate entrepreneur." By focusing on multi family 5 units or more, you are positioning yourself in a resilient asset class that provides stability, scale, and significant tax advantages.

Success is within your reach, and the "commercial" label shouldn't hold you back. With the right lending partner, the process is streamlined and designed to help you win. 2026 is seeing a massive wave of investors realizing that 10 houses are much harder to manage than one 10-unit building. Don't get left behind in the residential grind.

Ready to see what your first 5-10 unit deal looks like?

At Emerald Capital Funding, we thrive on helping investors scale. Whether you’re looking for a long-term DSCR solution or a short-term bridge to a massive renovation, we have the commercial loan products to make it happen.

Contact Bill Nicholson and the team today to discuss your next multi-family move. Let’s build that empire together.

Hard Money Horror Stories: The 3 Deadliest Mistakes in Fix & Flip Financing

If you’re considering jumping into the high-stakes world of real estate investing, welcome to one of the most exciting paths to wealth creation. There is something uniquely satisfying about taking a neglected property and transforming it into a beautiful home while turning a healthy profit. However, behind every glossy "after" photo you see on social media, there is often a hidden story of stress, late nights, and, if the investor isn't careful, financial ruin.

At Emerald Capital Funding, we’ve seen it all. We’ve watched seasoned pros scale their empires and we’ve seen newcomers lose their shirts because they fell into avoidable traps. Most "horror stories" in this industry don’t actually start with a leaky roof or a cracked foundation; they start at the closing table with the wrong financing.

This guide will equip you with the knowledge to identify the three deadliest mistakes in fix-and-flip financing so you can ensure your next project is a success story, not a cautionary tale.

1. The Turtle Trap: Why Slow Financing is the Ultimate Deal Killer

In the real estate world, speed isn't just a luxury, it’s a primary weapon. If you’ve spent any time looking for distressed properties, you know that the best deals are gone in a matter of hours, not days.

The first "horror story" often begins when an investor tries to use a traditional bank or a slow-moving hard money lender for a fast-paced flip. Traditional lenders are built for stability, not speed. They require mountains of documentation, extensive personal financial audits, and multi-week underwriting processes. In many cases, a traditional appraisal alone can add 10 to 15 business days to your timeline.

Why Speed Matters

When you are negotiating with a wholesaler or a motivated seller, they aren't just looking for the highest price; they are looking for the most certain exit. If you come to the table with a lender who takes 45 days to close, you will lose the deal to the investor who can close in five.

The Mistake: Choosing a lender based solely on the lowest interest rate without considering their speed of execution. A 1% lower interest rate means nothing if the property is sold to someone else while you’re waiting for an appraisal.

The Reality of Generic Hard Money: Not all hard money is created equal. Some "generic" lenders aren't actually structured for renovations. They might offer the capital for the purchase but have no infrastructure to handle construction draws (the process of releasing funds as work is completed). This leads to "draw gridlock," where your contractors are sitting idle because the lender is taking two weeks to send an inspector to the site.

A silver pocket watch and house keys representing the importance of fast hard money financing for fix and flips.

Actionable Takeaways:

  • Vet your lender’s "Speed to Lead": Ask specifically how many days it takes from application to funding.
  • Prioritize in-house underwriting: Look for lenders like Emerald Capital Funding who handle the process internally rather than outsourcing to a third party.
  • Have your "Proof of Funds" ready: Before you even bid, ensure your lender has vetted your basic financials so you can strike when the iron is hot.

2. The Math Trap: Underestimating Costs and Inefficient Capital Allocation

If you want to stay in the flipping business, you have to be a master of the spreadsheet. The second deadliest mistake investors make is what we call "The Math Trap." This happens in two ways: underestimating the actual cost of the renovation and failing to structure the loan to protect your liquidity.

Underestimating the Rehab

Even experienced flippers face unexpected expenses. Whether it’s unpermitted electrical work found behind a wall or a sudden spike in lumber prices, projects almost always exceed the initial budget. Most investors who lose money do so because they didn't build in a financial contingency buffer.

The "100% Funding" Illusion

You may see lenders advertising "100% purchase and 100% renovation" loans. While these sound great, the devil is in the details. Many of these loans are capped at a percentage of the After-Repair Value (ARV), usually around 70%. If your purchase price and rehab costs exceed that 70% mark, you are suddenly on the hook for the difference, often at the exact moment you can least afford it.

Furthermore, many investors drain their personal cash reserves to cover the acquisition, leaving them "house rich and cash poor." When the renovation begins, they realize they have to self-fund the first phase of work before the lender releases the first draw. If you don't have the cash to get the work started, the project stalls, interest payments (carrying costs) pile up, and the horror story begins.

Actionable Takeaways:

  • The 20% Rule: Always add a 10% to 20% contingency buffer to your renovation budget for the "unforeseens."
  • Calculate your Carrying Costs: Don't just look at the rehab; account for monthly interest payments, taxes, insurance, and utilities.
  • Preserve Liquidity: Use leverage strategically. It is often better to put a little more down and keep cash in the bank for emergencies than to try and finance 100% and have zero breathing room.

Architectural blueprints and a calculator symbolizing accurate financial planning for real estate investment.

3. The Term Length Trap: Why Your Exit Strategy Needs More Breathing Room

This is perhaps the most heartbreaking mistake because it usually hits right when the finish line is in sight. Many investors opt for the shortest possible loan term (often 6 months) to save on extension fees or because they are overconfident in their timeline.

The Reality Check: Most fix-and-flip projects take longer than expected. Between delayed materials, overbooked subcontractors, weather delays, and the dreaded city permitting office, a "3-month flip" can easily turn into an 8-month marathon.

The Danger of a Maturing Loan

When your hard money loan reaches its "maturity date" and you haven't sold the property or refinanced, you are in a position of extreme weakness. Some predatory lenders use this as an opportunity to charge massive penalty fees or even start foreclosure proceedings to take the equity you’ve worked so hard to build.

Even if the lender is friendly, being forced to sell a property quickly because your loan is due means you might have to take a lower offer, effectively "losing your shirt" on the backend of the deal.

The Power of the 12-to-15 Month Term

At Emerald Capital Funding, we often suggest that investors look for longer terms, even if they plan to be out in six months. Having a 12 or 15-month term gives you the "breathing room" to handle a market dip or a contractor dispute without the sword of Damocles hanging over your head.

Actionable Takeaways:

  • Be Realistic, Not Optimistic: Double your estimated renovation time when choosing your loan term.
  • Check Extension Options: Before signing, ensure your loan agreement has clear, affordable extension options.
  • Have a Plan B: Always know what your "refinance" exit strategy is if the property doesn't sell as quickly as you hoped.

A beautifully renovated modern kitchen showing a successful fix and flip project completion and exit strategy.

How Emerald Capital Funding Helps You Avoid These Pitfalls

At Emerald Capital Funding, we don't just see ourselves as a source of capital; we see ourselves as your partner in the deal. We know that our success is directly tied to yours. We’ve designed our services specifically to combat the "horror stories" mentioned above.

  • Speed that Competes: We offer in-house underwriting and a streamlined process to help you close deals while other investors are still waiting on paperwork.
  • Transparent Draw Schedules: We understand that money needs to flow at the same pace as the construction. Our draw process is designed to keep your contractors paid and your project moving.
  • Expert Guidance: Our team, led by experts like Bill Nicholson, looks at your math with you. If we see a budget that looks too thin or a timeline that looks too aggressive, we’ll tell you. We’d rather lose a deal than watch a client lose their shirt.

If you’re ready to start your next project with a lender who understands the nuances of the market, you can apply now or contact us to discuss your scenario.


Common Questions About Fix & Flip Financing (Q&A)

Q: Why is hard money better than a bank loan for a flip?
A: Speed and flexibility. Banks rarely lend on properties in poor condition. Hard money lenders look at the potential value of the property (ARV) and can fund in a fraction of the time, allowing you to secure deals that banks would reject.

Q: How much cash do I actually need to bring to a deal?
A: While it varies, you should typically expect to bring 10-20% of the purchase price plus closing costs and enough liquid cash to fund the first phase of renovations before your first draw is released.

Q: What is a "Construction Draw"?
A: This is the process where the lender releases portions of the renovation budget as specific milestones are met (e.g., after the plumbing is roughed in or the roof is completed).

Q: Can I flip a house with no experience?
A: Yes, but your financing might be more expensive, or you may require a lower LTV (Loan to Value). Having a solid contractor and a detailed line-item budget is the best way to gain a lender's confidence as a beginner.

Q: What happens if my loan expires before I sell?
A: You will need to either pay an extension fee (if available), refinance into a long-term rental loan (DSCR loan), or pay off the balance. This is why having an exit strategy is vital.

Final Thoughts

Success in real estate investing is within your reach, provided you approach it with a systematic, disciplined strategy. By avoiding the "Turtle Trap" of slow financing, steering clear of the "Math Trap" with proper capital allocation, and giving yourself plenty of "Breathing Room" with your loan terms, you’ll be well on your way to a profitable exit.

Don't let your investment dreams turn into a horror story. Work with a lender who has the experience and the professional tone to guide you through the complexities of the market. With the right approach and the right partner, you can achieve your financial goals and build a pathway to long-term security.

Ready to get started? Click here to Apply Now and let’s get your deal funded.

The ‘Stabilization Playbook’: Using Bridge Loans to Force Appreciation Before Flipping to DSCR

If you’re looking to scale your real estate portfolio in 2026, you’ve likely realized that the “easy” deals: those turnkey properties that cash flow perfectly from day one: are harder to find than ever. To really win in today's market, you need a strategy that doesn’t just rely on market timing but creates value where none existed before.

Welcome to the world of the Stabilization Playbook.

At Emerald Capital Funding, we see the most successful investors moving away from traditional “buy and hold” and toward a more sophisticated "buy, stabilize, and refinance" model. This guide will equip you with the knowledge to use bridge loans as a catalyst for forced appreciation, allowing you to eventually lock in long-term wealth with a DSCR loan.

Whether you’re a seasoned pro or just getting your feet wet, we’ve got you covered. Success within your reach starts with understanding how to bridge the gap between a "fixer" and a "fortress."

Phase 1: The Bridge Loan – Your Tool for Speed and Agility

Before we dive into the renovations, we need to talk about the fuel for your engine: the bridge loan.

A bridge loan is a short-term financing solution designed to “bridge” the gap between the purchase of a distressed or underperforming asset and its eventual long-term financing or sale. While traditional banks might take 45 to 60 days to close (and likely reject a property that needs significant work), a bridge loan from a private lender like Emerald Capital Funding can often close in a fraction of that time.

Why Bridge Loans Are Essential for Stabilization:

  • As-Is Lending: Unlike conventional mortgages, bridge loans are based on the property’s potential and current condition, not just your personal tax returns.
  • Speed: In a competitive market, being able to close in 7 to 10 days is a superpower.
  • Interest-Only Payments: Most bridge loans feature interest-only payments, which helps keep your carrying costs low while the property is vacant and under construction.
  • Renovation Financing: Many bridge products allow you to wrap the cost of the rehab into the loan itself.

Actionable Takeaway: Use bridge loans for the "ugly" phase of the project. Don't worry about the higher interest rate compared to a 30-year fixed; you aren't staying in this loan for long. Think of it as a tool, not a long-term commitment.

Blueprints for a real estate renovation project funded by a bridge loan for property stabilization.

Phase 2: Mastering the Art of Forced Appreciation

Once you’ve secured the property with a bridge loan, the real work: and the real profit: begins. This is where you "stabilize" the asset. In real estate terms, stabilization means taking a property from a state of vacancy, disrepair, or under-market rents to a state of being fully renovated, occupied by reliable tenants, and generating market-leading income.

This process creates Forced Appreciation. Unlike natural appreciation (waiting for the neighborhood to get nicer), forced appreciation is entirely within your control. You are increasing the value of the property by improving its physical condition and its financial performance.

How to Force Appreciation:

  1. Strategic Renovations: Focus on high-ROI upgrades like kitchens, bathrooms, and "curb appeal" (landscaping and exterior paint).
  2. Operational Efficiency: If it’s a multi-family property, look for ways to decrease expenses, such as sub-metering utilities or improving property management.
  3. Increasing Income: Renting out the units at the top of the market after renovations are complete.
  4. Adding Value-Add Units: Turning a large basement into an ADU (Accessory Dwelling Unit) or converting a 2-bedroom into a 3-bedroom.

Actionable Takeaway: Always have your "Exit Value" in mind before you swing a hammer. Your goal is to increase the property's value enough that you can recoup your initial investment during the refinance phase.

The Math: How Forced Appreciation Works in Real Time

Let's look at the numbers. This is where the Stabilization Playbook proves its worth. Imagine you find a distressed duplex in a growing neighborhood.

  • Purchase Price: $300,000
  • Rehab Budget: $60,000
  • Total Cost Basis: $360,000

If you bought this with a bridge loan from Emerald Capital Funding, you might have only put 15% down on the purchase and financed 100% of the rehab.

Now, let's say after six months of stabilization, the property is fully renovated and rented for $2,000 per unit ($4,000 total monthly income). Based on comparable sales and the new income stream, the new appraised value (After Repair Value or ARV) is $500,000.

The Forced Appreciation Calculation:

  • New Value: $500,000
  • Total Investment: $360,000
  • Equity Created: $140,000

With that said, you have now created $140,000 in wealth in just a few months. But you're still sitting in a short-term bridge loan. Now it’s time for the final move.

Modern renovated kitchen showing forced appreciation and increased equity for a DSCR loan refinance.

Phase 3: The Exit Strategy: Flipping to a DSCR Loan

The final step of the playbook is to transition from your short-term bridge loan into a long-term, low-stress DSCR loan.

DSCR stands for Debt Service Coverage Ratio. These loans are a favorite for real estate investors because they don’t look at your personal income or debt-to-income (DTI) ratio. Instead, the lender looks at one thing: Does the property’s rent cover the mortgage payment?

Why Flip to DSCR?

  • No Tax Returns Required: Perfect for self-employed investors who have significant write-offs.
  • Cash-Out Refinance: Because you forced the appreciation to $500,000, you can now do a cash-out refi at 75% LTV (Loan-to-Value).
    • Calculation: 75% of $500,000 = $375,000.
  • Recouping Capital: Your new loan of $375,000 pays off your $360,000 bridge loan and rehab costs, and leaves you with $15,000 in your pocket: plus a fully stabilized, cash-flowing asset with $125,000 in remaining equity.

Once you've reached this stage, you have successfully "recycled" your capital. You have a long-term rental property that pays for itself, and you have your original investment back in your bank account, ready to use for the next deal.

Actionable Takeaway: Ensure your stabilized rent is high enough to achieve a DSCR ratio of at least 1.20 (meaning the rent is 20% higher than the mortgage payment). This will give you the best rates and terms.

Common Hurdles and How to Clear Them

Even the best playbooks have challenges. Here is how to handle the most common ones:

  • The Appraisal Gap: Sometimes the ARV comes in lower than expected. To avoid this, always work with a lender like Emerald Capital Funding who understands investor-grade appraisals and can help you vet your numbers upfront.
  • Construction Delays: Stabilization takes time. Make sure your bridge loan has a term long enough to handle hiccups. Our 15-month terms are designed specifically to give you that breathing room.
  • Tenant Issues: A property isn't stabilized until it has a paying tenant. Don't rush the screening process; a bad tenant can ruin your DSCR refi chances if they stop paying during the application process.

House keys and financial documents representing a successful DSCR loan exit and rental income growth.

Q&A: Specifics of the Stabilization Strategy

Q: Can I use this strategy for commercial properties?
A: Absolutely. In fact, forced appreciation is even more powerful in commercial real estate (5+ units) because the value is directly tied to the Net Operating Income (NOI). Increasing rent by $100 per unit on a 10-unit building can increase the property value by six figures depending on the cap rate.

Q: How long do I have to wait to refinance from a bridge loan to a DSCR loan?
A: This depends on "seasoning" requirements. Some lenders require you to own the property for 3-6 months, while others allow for an immediate refinance if the renovations are documented. We can help you navigate these timelines at Emerald Capital Funding.

Q: What is the minimum credit score for this playbook?
A: Generally, you’ll want a score of 660 or higher to get the most competitive rates on both the bridge and the DSCR exit, though options exist for lower scores depending on the equity in the deal.

Q: Do I need to be an experienced flipper to do this?
A: Not necessarily, but you do need a solid team. If it's your first time, hiring a reputable general contractor is the best way to ensure the stabilization goes according to plan.

Conclusion: Start Building Your Portfolio Today

The 'Stabilization Playbook' is the pathway to financial security for the modern investor. By leveraging the speed of bridge loans to force appreciation and the stability of DSCR loans to hold for the long term, you can scale your portfolio faster than you ever thought possible.

Don't let market conditions slow you down. With the right approach and a partner who understands the math of real estate, your success is well within reach.

Ready to see how the numbers look for your next deal? Whether you're eyeing a fixer-upper or ready to refinance a stabilized asset, we're here to help you cross the finish line.

Apply Now with Emerald Capital Funding and let's get your stabilization project off the ground! Or, if you have questions about our rates and terms, feel free to Contact Us today. Your next great investment is just one bridge loan away.

The ‘Fix and Flip’ Blueprint: How to Secure 90% LTC and Maximize Your ROI

If you’re considering diving into the fast-paced world of real estate renovation or you're a seasoned pro looking to optimize your capital, welcome. You’ve probably seen the "Before and After" photos that make fix-and-flip investing look like a breeze, but behind every successful transformation is a rock-solid financial strategy. In 2026, the market doesn't just reward those with an eye for design; it rewards those with the best leverage.

At Emerald Capital Funding, we see investors every day who have found the "perfect" property but struggle to find the right way to pay for it. This guide will equip you with the tactical knowledge you need to master fix and flip financing, specifically focusing on how to secure 90% Loan-to-Cost (LTC) and 100% of your rehab funds. With the right approach, success is well within your reach.

Understanding the Fundamentals: LTC vs. LTV

Before we dive into the deep end, it’s vital to understand the language of the trade. If you’ve dealt with traditional mortgages, you’re used to LTV (Loan-to-Value). However, in the world of hard money loans, we talk about LTC.

  • LTV (Loan-to-Value): This is based on the appraised value of the property.
  • LTC (Loan-to-Cost): This is based on the total cost of the project: the purchase price plus the renovation budget.

Why does this matter? Because 90% LTC means you are only bringing 10% of the total project cost to the closing table as a down payment. This preserves your liquidity, allowing you to move onto your next deal faster. For a more detailed breakdown, check out our fix and flip loan basics.

Modern blueprints and coins representing strategic planning for a 90% LTC fix and flip loan.

The Power of 90% LTC and 100% Rehab Funding

In the current lending landscape, the "Emerald Advantage" is built on maximizing your leverage. Most traditional banks will look at a fix-and-flip project and see too much risk. They might offer 65% or 70% of the purchase price and expect you to fund the entire renovation out of pocket.

At Emerald Capital Funding, we flip that script. We offer:

  • Up to 90% LTC on the purchase price.
  • 100% of the renovation costs.

By funding 100% of the rehab, we ensure that your capital isn't tied up in drywall and plumbing. Instead, that money stays in your bank account as a safety net or as a down payment for your next project. This level of financing is a pathway to financial security because it allows you to scale your business rather than just doing one house at a time.

How the Math Works: An Example

Imagine you find a distressed property for $200,000 that needs $50,000 in work. The After-Repair Value (ARV) is estimated at $350,000.

  • Total Project Cost: $250,000.
  • 90% LTC Financing: We provide $225,000.
  • Your Down Payment: Only $25,000 (plus closing costs).

Compare that to a traditional loan where you might need $60,000 for the down payment and $50,000 for the rehab: a total of $110,000 out of pocket. With our fix-and-flip secrets revealed, you keep an extra $85,000 in your pocket.

Strategic Planning to Maximize Your ROI

Securing the loan is only half the battle; maximizing your Return on Investment (ROI) is where the real money is made. To achieve your financial goals, you need a systematic, step-by-step approach to the project itself.

1. The 70% Rule Still Reigns

While 2026 has brought new market dynamics, the "70% Rule" remains a gold standard for professional flippers. The rule suggests that you should never pay more than 70% of the ARV, minus the cost of repairs.

  • Formula: (ARV x 0.70) – Rehab Costs = Maximum Purchase Price.
    Using this formula helps you build in a "margin of safety" for the unexpected costs that inevitably arise.

2. Time is Your Greatest Expense

In the world of hard money loans, interest is a carrying cost. Every day the house sits empty is a day you are paying for utilities, insurance, property taxes, and loan interest.

  • Pro Tip: Have your contractors lined up before you close.
  • Pro Tip: Secure permits early.
    By shaving just 30 days off your renovation timeline, you can significantly boost your net profit.

3. Focus on "High Impact" Renovations

Don't over-improve for the neighborhood. If the comps in the area have laminate countertops, installing Carrara marble won't necessarily increase your ARV, but it will definitely decrease your ROI. Focus on:

  • Kitchen updates (cabinets, hardware, lighting).
  • Bathroom refreshes.
  • Curb appeal (landscaping and exterior paint).
  • Clean, neutral interior paint and modern flooring.

A luxury kitchen renovation featuring high-end finishes to maximize ROI on a fix and flip project.

Speed: Your Secret Weapon in 2026

If you've ever tried to get a construction loan from a big-box bank, you know it's a slow slog. They want three years of tax returns, your high school transcripts, and a month to "review the file." In the time it takes them to open your email, a cash buyer or an investor with Emerald Capital Funding has already closed the deal.

We focus on the property and your experience, not just your personal debt-to-income ratio. This is why conventional loan rehab vs. hard money isn't even a fair fight when it comes to speed. We move at the speed of the market, often closing in as little as 7 to 10 days.

Common Pitfalls to Avoid

Even with 90% LTC, things can go sideways if you aren't careful. Don't worry, though: most of these are preventable with a bit of foresight.

  • Underestimating Rehab Costs: Always add a 10-15% contingency to your budget for "unforeseen issues" (like the termites behind the shower wall).
  • Overestimating the ARV: Be conservative. Use recent sales within the last six months and stay within a half-mile radius.
  • Skipping the Inspection: Even if you’re buying "as-is," get an inspection so you know exactly what you’re getting into.

For more on this, check out our guide on common fix-flip mistakes.

Two investors shaking hands after successfully closing a fast-paced hard money loan deal.

The "Exit" Strategy: Selling vs. Refinancing

Once the renovation is complete, you have two primary options: Sell for a profit or keep it as a rental.

If the market is hot, selling is the fastest way to realize your ROI. However, many investors are now opting for the BRRRR strategy (Buy, Rehab, Rent, Refinance, Repeat). Once your flip is finished, you can transition from your short-term hard money loan into a long-term DSCR loan.

A DSCR loan allows you to pull your initial capital back out of the deal based on the new, higher value of the home, allowing you to grow your portfolio without needing fresh cash for every deal. We even have a 90-day BRRRR timeline guide to help you manage that transition perfectly.

Q&A: Fix and Flip Financing

Q: Does Emerald Capital Funding require a minimum credit score for 90% LTC?
A: While we look at credit, we are primarily asset-based lenders. We care more about the deal’s profitability and your track record. Generally, a score of 660+ gets you the best terms, but we have options for various profiles.

Q: How do "draws" work for the 100% rehab funding?
A: Once you complete a specific stage of work (e.g., plumbing and electrical), you request a draw. We send an inspector to verify the work, and then funds are released to you. It’s a transparent process designed to keep the project moving.

Q: Can I use this for a multi-family property?
A: Absolutely. We handle everything from single-family homes to 5+ unit commercial multi-family.

Q: What if I have no experience flipping houses?
A: We love working with new investors! While your leverage might be slightly lower on your first deal (e.g., 80-85% LTC), we provide the same speed and support to help you get that first win under your belt.

Reviewing a digital property floor plan on a tablet to secure 100% rehab funding.

Take Action Today

The difference between a "dream" and a "deal" is the financing behind it. With 90% LTC and 100% rehab funding, you can stop dreaming about flipping houses and start building a real estate empire.

Whether you’re looking at a small condo in the suburbs or a massive transformation in Norristown, PA, Emerald Capital Funding is ready to be your partner in growth. We’ve got you covered with the capital, the speed, and the expertise to ensure your next flip is a resounding success.

Ready to see what you qualify for? Apply Now and let’s get your next project funded. Your pathway to financial security starts with one smart move. Let’s make it happen together.

DSCR vs. Traditional: Why Your Personal Tax Returns Don’t Matter Anymore

If you’re considering expanding your real estate portfolio, you’ve likely hit the "tax return wall" at some point. You know the drill: you’ve worked hard to build a successful business, your CPA has done a fantastic job finding every legal deduction possible, and your taxable income looks modest on paper. Then, you walk into a traditional bank for a mortgage, and the loan officer gives you that sympathetic look before telling you that you don't "make enough" to qualify for another loan.

Welcome to the world of real estate investing, where traditional banking rules often feel like they were designed to hold you back rather than help you grow. At Emerald Capital Funding, we believe that your ability to scale shouldn't be limited by how well you manage your taxes.

In this guide, we’ll equip you with the knowledge of why DSCR loans are the ultimate tool for savvy investors and why, in our world, your personal tax returns are basically irrelevant.

The Traditional Lending Trap for Self-Employed Investors

Before we dive into the solution, let’s look at why the traditional path is so difficult for the modern investor. When you apply for a conventional mortgage, the lender uses a metric called Debt-to-Income (DTI). They look at your gross income from your tax returns, subtract your personal debts, and determine if you can afford the new mortgage.

For self-employed individuals, this is a nightmare. You might be cash-flow positive by $20,000 a month, but if your tax returns show heavy depreciation and business expenses that bring your "taxable income" down to $4,000 a month, the bank sees a high-risk borrower.

Common hurdles with traditional loans include:

  • The Two-Year Rule: Most banks require at least two years of consistent tax returns in the same industry.
  • The DTI Ceiling: Even if the property pays for itself, the bank still adds that mortgage to your personal debt profile, eventually capping how many houses you can own.
  • The "Paperwork" Marathon: Providing hundreds of pages of personal bank statements, pay stubs, and tax schedules for every single deal.

An investor overwhelmed by stacks of tax paperwork required for a traditional bank mortgage loan.

What Are DSCR Loans? (The Game Changer)

DSCR stands for Debt Service Coverage Ratio. Unlike a traditional loan that focuses on you, a DSCR loan focuses on the property.

The logic is simple: If the rental income from the property covers the mortgage payment (including taxes, insurance, and HOA), why does it matter how much you made at your day job or what your tax returns say?

To calculate the ratio, lenders take the Net Operating Income (NOI) or the gross monthly rent and divide it by the monthly debt service (PITIA).

  • A ratio of 1.0 means the property breaks even.
  • A ratio of 1.25 means the property generates 25% more income than the cost of the debt.

With DSCR loans, we aren't looking at your W2s. We aren't asking for your 1040s. We are looking at the property’s ability to pay for itself.

Actionable Takeaway:

Check your potential property's rent-to-debt ratio before applying. If the rent is $2,000 and the total mortgage payment is $1,600, your DSCR is 1.25. This is a "slam dunk" for most DSCR lenders.

Why Your Tax Returns Don't Matter Anymore

This is the part our clients at Emerald Capital Funding love the most. Because DSCR lending is "asset-based," we have moved away from the intrusive personal financial scrutiny of the 1990s. Here is why the shift in focus benefits you:

1. No Income Verification

We don't call your employer. We don't ask for profit and loss statements for your side hustle. We don't care about the deductions you took last year. This is a massive win for investors who are 1099 contractors or small business owners.

2. Rapid Scaling

With traditional loans, you eventually hit a "cap." Most conventional lenders won't let you have more than 10 properties in your personal name. Because DSCR loans don't rely on your personal DTI, you can theoretically scale to 20, 50, or 100 properties without your personal income ever becoming an issue.

3. Faster Closing Times

Tax return reviews are often the longest part of the underwriting process at a big bank. By removing them from the equation, we can move from application to closing much faster. Speed is the currency of real estate; winning a deal often depends on how fast you can get funded.

Modern house keys representing the speed and ease of securing an investment property with DSCR loans.

The Documentation You Actually Need

If we aren't looking at tax returns, what are we looking at? Don't worry, the list is much shorter and easier to manage. To secure a DSCR loan with Emerald Capital Funding, you’ll typically need:

  1. Credit Score: While we don't look at income, we do want to see that you have a history of paying your debts. A higher score often leads to better rates.
  2. Appraisal with a Rent Schedule (Form 1007): This is the most important document. An appraiser will verify what the property is worth and, more importantly, what the "market rent" is for that area.
  3. Lease Agreement: If the property is already occupied, we’ll need the current lease. If it’s vacant, we use the market rent from the appraisal.
  4. Liquidity (Reserves): We want to see that you have enough cash in the bank to cover a few months of payments in case of a vacancy.
  5. Entity Documents: Most investors close DSCR loans in an LLC. We’ll need your Operating Agreement and EIN.

Comparing the Two Paths: Conventional vs. DSCR

To help you visualize the difference, we’ve broken down the key features of each loan type:

Feature Traditional Bank Loan DSCR Loan (Emerald Capital)
Primary Qualifier Your Personal Income/Tax Returns Property’s Cash Flow
Employment Verification Extensive (W2s/Paystubs) None Required
Max Properties Owned Typically capped at 10 Virtually Unlimited
Closing Speed 45–60 Days 21–30 Days
Down Payment 15–25% 20–25%
Ownership Personal Name LLC or Personal Name

With that said, it's important to be aware of the trade-offs. DSCR loans usually come with slightly higher interest rates than a primary residence mortgage, often by 0.50% to 1.5%. However, most investors find that the ability to actually get the deal done and scale their portfolio far outweighs the slightly higher cost of capital.

A conceptual path showing the efficiency of scaling a portfolio with DSCR loans over traditional lending.

Scaling Secrets: The BRRRR Strategy and DSCR

One of the most powerful ways to use DSCR loans is in conjunction with the BRRRR (Buy, Rehab, Rent, Refinance, Repeat) strategy.

Many of our clients start with a bridge loan to purchase a distressed property and fund the renovations. Once the property is beautiful, rented out, and worth significantly more than the purchase price, they "exit" that short-term loan into a long-term DSCR loan.

This allows you to pull your initial capital back out of the deal based on the new appraised value, rather than being stuck because your tax returns don't support another refinance. You can learn more about this timeline in our guide on the 90-day BRRRR strategy.

Q&A: Common Questions About DSCR Loans

Q: Can I get a DSCR loan if the property is currently vacant?
A: Yes! We can use the "market rent" determined by the appraiser to calculate the ratio. This is very common for fix-and-flip investors transitioning to long-term rentals.

Q: Is there a minimum credit score required?
A: Generally, we like to see a credit score of 620 or higher. The better your score, the higher the leverage (LTV) we can provide.

Q: Can I use a DSCR loan for a short-term rental (Airbnb/VRBO)?
A: Absolutely. We have specific programs that use AirDNA data or actual short-term rental history to qualify the property’s income.

Q: What happens if the DSCR ratio is below 1.0?
A: We still have options! Some of our programs allow for "no-ratio" loans, though they may require a slightly larger down payment.

Professional handshake at a closing table for a successful real estate investment property loan.

Your Pathway to Financial Security

Success within your reach doesn't have to be complicated by outdated banking requirements. By shifting the focus from your personal tax returns to the strength of your real estate assets, you unlock a level of freedom that traditional lending simply can't offer.

At Emerald Capital Funding, we’ve got you covered. We understand the hustle of the self-employed investor because we work with them every day. We know that a "loss" on a tax return is often just a smart accounting move, not a reflection of your ability to manage a successful rental portfolio.

Whether you are looking to buy your first rental or your fiftieth, our team is here to help you navigate the process with ease and professionalism. Don't let your CPA’s hard work on your tax returns stop you from building a real estate empire.

Ready to see what you qualify for?

Skip the tax return headache and get a quote on your next investment property today.

Your next deal is waiting. Let’s get it funded.

From Bridge to BRRRR: The Exact Strategy for Rapid Portfolio Scaling

If you’re considering how to transform a single investment property into a massive real estate empire, you have likely heard of the BRRRR method. It is the gold standard for investors who want to scale quickly without needing a bottomless pit of personal cash. However, the "secret sauce" that many gurus leave out is exactly how to finance it to ensure the cycle never breaks.

Welcome to the world of high-velocity real estate investing. At Emerald Capital Funding, we specialize in the two financial pillars that make this strategy possible: bridge loans and DSCR loans. This guide will equip you with a step-by-step blueprint to navigate the Bridge-to-BRRRR pipeline, helping you achieve your financial goals with the confidence of a seasoned pro.

What is the BRRRR Strategy?

Before we dive into the mechanics of the money, let’s refresh the framework. BRRRR stands for Buy, Rehab, Rent, Refinance, Repeat.

The goal is simple: buy a property that needs work, renovate it to increase its value (forced appreciation), rent it out to cover the mortgage, and then perform a cash-out refinance to pull your initial capital back out. Once you have your cash back, you move on to the next deal.

The beauty of this method is that it allows you to recycle the same pool of capital over and over again. But to make it work, you need the right leverage at the right time.

House keys and real estate data on a desk representing a BRRRR bridge loan strategy.


Step 1: Buy – Winning the Deal with Bridge Loans

The first "B" is often where investors get stuck. If you try to use a conventional bank loan to buy a distressed property, you’ll likely be rejected. Traditional banks want "move-in ready" homes. This is where bridge loans (short-term financing used to "bridge" the gap until long-term debt is secured) become your greatest asset.

When you use a bridge loan from a lender like Emerald Capital Funding, you aren't just getting a mortgage; you’re getting speed and flexibility. Bridge loans are often based on the After-Repair Value (ARV) or the Loan-to-Cost (LTC) ratio rather than just the current purchase price.

  • Speed is your weapon: In a competitive market, being able to close in 10-14 days with a bridge loan allows you to beat out buyers waiting on 45-day conventional approvals.
  • Leverage your capital: We often provide up to 90% of the purchase price and 100% of the renovation costs. This keeps your "skin in the game" to a minimum.

Actionable Takeaway: Before you make an offer, get pre-approved for a bridge loan. Knowing your numbers: specifically your LTC: will help you move faster than the competition. Check out our Bridge Loans Simplified page to see how we structure these.


Step 2: Rehab – Creating "Forced Appreciation"

The "Rehab" phase is where the magic happens. Your goal isn't just to make the house pretty; it’s to increase the property’s value strategically so that the new appraisal comes in significantly higher than your total investment.

Expert investors follow the 70% Rule: Your total investment (purchase price + rehab costs) should not exceed 70% of the estimated After-Repair Value.

  • Focus on High-ROI Upgrades: Prioritize kitchens, bathrooms, and "curb appeal" (paint, landscaping).
  • Stay on Budget: Every dollar you overspend on the rehab is a dollar you might not get back during the refinance stage.

Actionable Takeaway: Maintain a detailed "draw schedule" for your rehab. Because bridge lenders release renovation funds in stages (draws), having a clear plan ensures the project never stalls due to a lack of cash flow. For more tips on this, read our Fix and Flip Secrets Revealed.


Step 3: Rent – Stabilizing the Asset

Once the renovation is complete, you need to "Rent" the property. This step is crucial because it turns your "fix and flip" project into a "buy and hold" asset.

Most long-term lenders: especially those offering DSCR loans: require the property to be "stabilized." This means having a signed lease and, often, the first month's rent and security deposit collected.

  • Screen for Quality: A bad tenant can ruin your refinance. Lenders want to see stable, reliable income.
  • Aim for the 1% Rule: Ideally, your monthly rent should be at least 1% of the total purchase and rehab cost to ensure strong cash flow.

Modern renovated living room interior ready for rental and a cash-out DSCR loan refinance.


Step 4: Refinance – The Cash-Out Strategy with DSCR Loans

This is the most critical pivot point in the strategy. Once the property is rehabbed and rented, you need to move out of that high-interest bridge loan and into a long-term, low-interest mortgage.

We recommend using a DSCR Loan (Debt Service Coverage Ratio). Unlike traditional mortgages that look at your personal income and tax returns, a DSCR loan focuses entirely on the property’s ability to pay for itself.

  • No Tax Returns Required: If the rental income covers the mortgage payment (a ratio of 1.0 or higher), you’re in the clear.
  • Cash-Out Refinance: Because the property is now worth more than when you bought it, you can refinance based on the new appraised value. This allows you to pay off the bridge loan and "pull out" the initial cash you used for the down payment.

With the right timing, you can achieve a "perfect BRRRR," where you have $0 of your own money left in the deal, yet you own a cash-flowing asset with 20-25% equity.

Actionable Takeaway: Start the conversation with your long-term lender during the rehab phase. Understanding the 90-day BRRRR timeline is essential to avoid paying extra interest on your bridge loan longer than necessary.


Step 5: Repeat – Scaling Your Portfolio

With your initial capital back in your bank account and a tenant paying down your new DSCR mortgage, you are ready to Repeat.

This is how investors go from owning one property to owning ten or twenty in just a few years. By recycling the same $50,000 or $100,000, you aren't limited by your personal savings rate: you’re only limited by your ability to find good deals.

Row of house models increasing in size symbolizing rapid real estate portfolio scaling.


Why Every Serious Investor Needs a DSCR Loan in Their Toolbox

Scaling a portfolio requires moving away from the "W-2 mindset." Conventional lenders have limits on how many mortgages you can have (usually 10). DSCR loans, however, allow for unlimited scaling. As long as the properties make sense financially, Emerald Capital Funding can keep funding your growth.

Whether you are looking at single-family homes or making the jump to 5+ unit multi-family properties, having a lender who understands the BRRRR cycle is your competitive advantage.


Q&A: Common Questions About the Bridge-to-BRRRR Strategy

Q: How long do I have to wait to refinance a bridge loan into a DSCR loan?
A: This is known as the "seasoning period." While some conventional banks require 6-12 months, many DSCR lenders can refinance you as soon as the property is renovated and a tenant is in place. In some cases, there is no seasoning requirement at all if you aren't doing a "cash-out" above your total cost.

Q: What is a "good" DSCR ratio?
A: Most lenders look for a 1.2x ratio (meaning the rent is 20% higher than the debt payment), but we have programs that go down to 1.0x or even "no ratio" for certain high-equity deals.

Q: Can I use this strategy for multi-family properties?
A: Absolutely. In fact, scaling is often faster with multi-family units, though the financing rules change slightly once you cross into the 5+ unit territory.

Q: What happens if the appraisal comes in low?
A: This is a risk in any BRRRR. To mitigate this, we always suggest being conservative with your initial ARV estimates. If the appraisal is low, you may have to leave some "forced equity" in the deal rather than pulling all your cash out.

Real estate investor using a smartphone to manage a scaled portfolio and financial growth.


Your Pathway to Financial Security

Scaling a real estate portfolio doesn't have to be a slow, decades-long crawl. By leveraging the Bridge-to-BRRRR strategy, you can accelerate your growth and build a legacy of passive income.

At Emerald Capital Funding, we provide the financial tools: from high-leverage bridge loans to long-term DSCR solutions: to make your vision a reality. Success is within your reach, and we’ve got you covered every step of the way.

Ready to start your next deal?
Apply Now to get a quote, or Contact Us to speak with a lending expert about your strategy. Let’s build your empire together.

Conventional Loan Rehab is Too Slow: Why Pro Investors are Using Hard Money to Win in 2026

If you’re considering scaling your real estate portfolio this year, welcome to the world of high-speed investing. In 2026, the market isn't just about who has the best eye for a property; it’s about who can get to the closing table first. Whether you are a seasoned pro or just starting your journey, the way you finance your acquisitions will determine whether you’re collecting keys or just collecting "better luck next time" emails.

For years, the conventional loan rehab was the go-to for many. Programs like Fannie Mae HomeStyle or FHA 203(k) offered low interest rates and a path to renovation. However, in today's competitive landscape, these "slow and steady" options are often the very thing standing between you and a profitable deal. At Emerald Capital Funding, we’ve seen a massive shift toward hard money loans, and for good reason.

This guide will equip you with the knowledge to understand why traditional financing is lagging and how you can leverage speed to dominate your local market.

The Conventional Loan Rehab Bottleneck: Why "Cheap" Money Costs You More

Before we dive into the solutions, we need to address the elephant in the room: the conventional lending process is fundamentally broken for the modern investor. When you use a conventional rehab loan, you aren't just borrowing money; you are entering into a long-term relationship with a bureaucratic machine.

The Inspection and Approval Marathon

Conventional rehab loans require an exhaustive series of hurdles. You need pre-approvals, detailed property inspections, multiple contractor bids, and intensive underwriting. If you are looking at a distressed property, the kind that offers the best margins, a conventional lender might reject the deal outright because the home isn't "habitable" in its current state.

The Rehab Draw Nightmare

Once you actually close (which can take 45 to 60 days), the trouble doesn't stop. Research indicates that rehab draw inspections are a major pain point. Conventional lenders often have rigid milestones. If there is a slight mismatch between your project scope and your progress, or if your documentation is missing a single receipt, the lender can freeze your funds. This triggers secondary reviews and halts your construction, costing you thousands in holding costs.

The Competition Gap

In 2026, sellers want certainty. If a seller receives two offers, one with a conventional rehab contingency that takes two months to close and one with a hard money loan that can close in seven days, the faster offer wins every time, even if it’s for a slightly lower price.

House keys and smartphone on a desk showing the speed of hard money loans over slow conventional rehab paperwork.

Hard Money Loans: The Pro Investor’s Secret Weapon

With that said, why are professional investors increasingly turning away from banks and toward private capital? The answer lies in the fundamental difference in how these loans are structured. Hard money loans are asset-based. This means the lender cares more about the value of the property and the potential of the project than your personal debt-to-income ratio.

1. Lightning-Fast Closing Times

In the time it takes a conventional lender to schedule an appraisal, a hard money lender like Emerald Capital Funding can have your deal funded. We’re talking days, not months. This speed allows you to:

  • Snag off-market deals before they hit the MLS.
  • Compete with "all-cash" buyers.
  • Secure properties at a discount because you can solve the seller's problem quickly.

2. Focus on "As-Completed" Value (ARV)

Conventional lenders typically lend based on the current value of the home. Hard money lenders look at the After Repair Value (ARV). This allows you to borrow a higher percentage of the total project cost, including the renovation budget. If you want to dive deeper into the math, check out our guide on fix and flip secrets and LTC math.

3. Flexibility with "Ugly" Houses

If a house is missing a kitchen or has a hole in the roof, a conventional lender will run for the hills. A hard money lender sees opportunity. We understand that the "ugly" houses are where the profit is made. We provide the capital to fix those issues so you can create value where others see a liability.

Actionable Takeaway: If you find a deal that requires significant structural work, don't even waste your time with a conventional bank. Start your hard money application immediately to secure the property before someone else does.

A Side-by-Side Comparison: Speed and Documentation

To help you visualize the difference, let's look at how these two paths typically play out for a standard $300,000 fix-and-flip project.

Feature Conventional Rehab Loan Hard Money Loan (Emerald Capital)
Time to Close 45–60+ Days 7–10 Days
Credit Focus Strict (DTI, Tax Returns) Asset-based (The Deal)
Property Condition Must be mostly habitable Can be a total gut-job
Renovation Funds Released slowly with heavy red tape Flexible draw schedules
Competitive Edge Low (Sellers hate the wait) High (As good as cash)

As you can see, while the interest rate on a hard money loan might be higher than a conventional mortgage, the "cost of capital" is often lower when you factor in the deals you actually win and the speed at which you can turn over your capital.

Split view of a home renovation transformation funded by a fast fix and flip hard money loan.

The Strategy: The "Buy Fast, Refi Later" Method

Many investors worry about the higher interest rates of hard money. But pro investors don't keep hard money loans for 30 years, they use them as a bridge. This is often referred to as the BRRRR method (Buy, Rehab, Rent, Refinance, Repeat).

Here is how you can use this strategy to achieve financial security:

  1. Buy: Use a bridge loan or hard money to buy a distressed property quickly.
  2. Rehab: Use the lender’s renovation funds to fix the property and increase its value.
  3. Rent: Place a tenant to generate cash flow.
  4. Refinance: Now that the property is beautiful and habitable, move it out of the expensive hard money loan and into a long-term DSCR loan.
  5. Repeat: Take your initial capital out and do it all over again.

Because you’ve already completed the rehab, the refinance into a long-term loan is much smoother. You won't have to deal with the "rehab draw" headaches of a conventional loan because the work is already done. You can learn more about why every serious investor needs this in their toolbox by reading about DSCR loans explained.

Common Questions About Hard Money vs. Conventional Rehab

Q: Isn’t hard money too expensive for a first-time investor?
A: Actually, for a first-timer, hard money can be safer. A hard money lender acts as your partner; if we won't fund the deal, it’s probably because the math doesn't work. This "second set of eyes" can save you from a bad investment.

Q: Do I still need a down payment?
A: Yes, most hard money loans require some "skin in the game," typically 10-20% of the purchase price. However, we often fund 100% of the renovation costs.

Q: Can I use hard money for my primary residence?
A: Generally, no. Hard money is designed for business purposes and investment properties. If you’re looking to live in the home, conventional rehab loans are your best bet. But if you’re looking to make a profit, hard money is the way to go.

Professional handshake in a modern office symbolizing a successful partnership with a hard money lender.

Success is Within Your Reach with the Right Partner

Transitioning from conventional thinking to a "pro investor" mindset is a major milestone on your pathway to financial security. You don't have to let slow-moving banks dictate the pace of your growth. By choosing speed and flexibility, you position yourself to win more bids and complete more projects every year.

At Emerald Capital Funding, we specialize in providing the speed you need to compete in 2026. Whether you are looking for a fix and flip loan or a long-term DSCR solution, we’ve got you covered.

Ready to stop waiting and start winning?

Don't let the next great deal slip through your fingers while you wait for a bank to call you back. Contact us today or apply now to get your project funded in record time. Your next successful deal is just a click away.