Fix and Flip Secrets Revealed: The LTC Math Expert Lenders Use to Fund (or Reject) Your Deal

If you've ever had a fix and flip deal rejected and wondered why, chances are you ran headfirst into the twin gatekeepers of hard money lending: LTC and LTV. These aren't just alphabet soup acronyms lenders throw around to sound smart, they're the actual mathematical formulas that determine whether your deal gets funded or gets ghosted.

Here's the thing: most investors pitch their deals focusing on the wrong numbers. They talk about profit margins and ARV all day long, but they forget that lenders aren't your business partners, they're risk managers with calculators. And those calculators are programmed with specific formulas that either light up green or flash red the moment your deal crosses their desk.

Let's pull back the curtain and show you exactly how lenders at places like Emerald Capital Funding evaluate your fix and flip deals. Once you understand the math, you'll know how to structure your deals for approval before you ever hit "submit."

What Is LTC (And Why It's Your First Hurdle)

Loan-to-Cost (LTC) is the percentage of your total project cost that a lender is willing to finance. Think of it as the lender's way of making sure you have real skin in the game.

Here's the simple formula:

Maximum Loan Amount = LTC % × (Purchase Price + Renovation Budget)

Most fix and flip lenders offer LTC ratios between 70% and 90%, depending on your experience level, the property type, and the lender's risk appetite. New investors typically see 75% LTC, while seasoned flippers with proven track records might score 85-90%.
Calculator showing 75% LTC ratio for fix and flip loan with house model and cash investment

Let's say you find a distressed property for $150,000 and your contractor quotes $50,000 for renovations. Your total project cost is $200,000. If your lender offers 75% LTC, here's the math:

$150,000 (purchase) + $50,000 (rehab) = $200,000 total cost
75% × $200,000 = $150,000 maximum loan

That means you need to bring $50,000 of your own cash to the table. This is non-negotiable. The lender isn't going to suddenly become generous because you found a "great deal", the formula is the formula.

The Plot Twist: Meet the ARV LTV Cap

Here's where it gets interesting (and where many deals die). Lenders don't just calculate LTC and call it a day. They also run a second calculation based on your After-Repair Value (ARV) using a metric called LTV (Loan-to-Value).

The ARV LTV formula looks like this:

Maximum Loan Amount = LTV % × After-Repair Value

Most lenders cap ARV LTV at 70-75% for fix and flip loans. Using our example above, let's say your ARV is $280,000 and the lender uses a 70% ARV LTV cap:

70% × $280,000 = $196,000 maximum loan based on ARV

Now here's the kicker: the lender will always choose the lower of the two numbers.

In this scenario:

  • LTC gives you: $150,000
  • ARV LTV gives you: $196,000

You get $150,000 because it's the lower figure. The LTC was your limiting factor.
Fix and flip loan approval versus rejection comparison showing lender decision process

When the ARV LTV Becomes Your Enemy

Let's flip the scenario. Same property, same purchase price, same renovation budget, but this time your ARV is only $220,000 (maybe you were a bit optimistic, or the market shifted).

LTC calculation: 75% × $200,000 = $150,000
ARV LTV calculation: 70% × $220,000 = $154,000

You'd still get $150,000 because it's the lower number. But notice how close these numbers are getting? If your ARV was just $10,000 lower at $210,000, your ARV LTV would drop to $147,000, meaning you'd only get $147,000 in financing, even though the LTC formula says you should get $150,000.

This is why lenders order their own appraisals and why they're so skeptical of your contractor's ARV estimates. They're not being difficult, they're protecting themselves from overleveraging on a property that might not be worth what you think it is.

Why This Dual-Constraint System Exists

You might be wondering why lenders bother with two separate calculations instead of just picking one. It's simple: they're covering their bases from two different angles.

The LTC ratio ensures you contribute meaningful capital upfront. If you only put in 10% of the project cost and things go sideways, you might just walk away. But if you've got $50,000 of your own money on the line? You're far more likely to see the project through.

The ARV LTV cap protects the lender if your property value estimate is inflated. Real estate markets can shift, renovations can miss the mark, and comparable sales can be misleading. By capping the loan at 70-75% of ARV, the lender ensures they can recoup their investment even if they have to foreclose and sell at a discount.

How to Present Your Deal for Approval

Now that you understand the math, here's how to structure your deal presentation to maximize your approval odds:

1. Be Conservative with Your ARV
Use actual comparable sales from the past 90 days, not aspirational pricing. If anything, round down slightly. Lenders will verify this anyway, and being realistic builds trust.

2. Show Your Renovation Budget in Detail
Don't just throw out a round number. Break it down by line item with contractor bids. This shows you've done your homework and aren't just guessing.

3. Demonstrate Your Cash Reserves
Have proof you can cover your down payment plus at least 3-6 months of holding costs. Lenders want to see you can weather delays without defaulting.

4. Highlight Your Experience
If you've successfully completed previous flips, showcase them. Track record matters. If you're new, partner with an experienced flipper or bring a detailed project plan.

5. Run the Numbers Before You Apply
Don't wait for a lender to reject your deal. Calculate both your LTC and ARV LTV limits beforehand using conservative assumptions. If the numbers don't work, restructure the deal or walk away.
Property appraisal documents and house models for fix and flip deal preparation

Common Mistakes That Trigger Rejection

Overestimating ARV: This is the number one killer. Investors get emotionally attached to their deals and inflate values. Use conservative comps and adjust for market conditions.

Underestimating Renovation Costs: That $50,000 budget can easily become $70,000 once you start opening walls. Pad your estimates by 15-20% for contingencies.

Ignoring the Lower-of-Two Rule: Some investors run the LTC calculation, see they can borrow 75%, and assume they're golden. Then they're shocked when the ARV LTV cap reduces their financing.

Insufficient Cash Reserves: Even if the loan math works, lenders want to see you have breathing room. Running into a project with zero cushion is a red flag.

Poor Property Selection: Some properties just don't fit fix and flip financing parameters. Properties in declining markets, oversaturated areas, or with title issues will get rejected regardless of the math.

Q&A: Your Burning LTC Questions Answered

Q: Can I negotiate a higher LTC ratio?
A: Sometimes, yes, but only if you bring compensating factors like significant experience, strong credit, substantial reserves, or properties in prime markets. Don't expect first-time flippers to get 90% LTC.

Q: What if my renovation budget increases mid-project?
A: Most lenders won't increase your loan after closing. You'll need to cover overruns with your own capital. This is why conservative budgeting matters.

Q: Do all lenders use the same LTC and LTV percentages?
A: No. Each lender sets their own parameters based on risk tolerance. Shop around, but understand that significantly higher ratios usually come with higher interest rates or points.

Q: How quickly can I get funded once I understand these formulas?
A: With the right lender and complete documentation, fix and flip loans can close in 7-14 days. The math itself is instant: it's the due diligence that takes time.

Q: What's the minimum down payment I should expect?
A: Plan for at least 20-25% of total project cost for most fix and flip deals. Experienced investors might get away with 15%, but 25% is the safe assumption for planning purposes.
Investors reviewing renovation budget spreadsheet for fix and flip project planning

The Bottom Line

The math lenders use isn't designed to keep you out: it's designed to keep bad deals out. Once you understand the dual-constraint system of LTC and ARV LTV, you can structure your fix and flip projects to align with what lenders are actually looking for.

Run your numbers conservatively. Build in cushions. Present detailed, realistic projections. And remember: the goal isn't to maximize your leverage: it's to get funded on deals that actually make money.

When you approach your next flip with this knowledge, you'll stop guessing why deals get approved or rejected. You'll know. And that knowledge is the difference between investors who struggle to find financing and investors who get deals funded consistently.

Ready to Get Your Fix and Flip Funded?

At Emerald Capital Funding, we work with investors who understand the numbers and want a straight-shooting lender who won't waste their time. If you've got a deal that pencils out and you're ready to move quickly, let's talk. We close fix and flip loans fast because we know your profits are sitting in that renovation timeline: not stuck in endless underwriting.

Check out our Fix & Flip Loan Basics page to learn more about our programs, or reach out directly to discuss your next project. The calculator is ready. The question is: is your deal?

Why Every Serious Investor Needs a DSCR Loan in Their Toolbox

If you're building a real estate portfolio in 2026, you've probably hit this wall: traditional lenders want to see your tax returns, W-2s, pay stubs, and basically your entire financial life story before they'll fund another property. And if you're self-employed, own multiple LLCs, or simply want to scale faster than your personal debt-to-income ratio allows? Good luck.

Here's the thing, there's a financing tool that flips that script entirely. DSCR loans (Debt Service Coverage Ratio loans) qualify you based on what the property makes, not what you make. And for serious investors who want to grow their portfolios without getting buried in paperwork or hitting artificial lending limits, this is the game-changer you need in your toolbox.

What Exactly Is a DSCR Loan?

Before we dive into why this matters, let's get clear on what we're talking about.

A DSCR loan is a type of investment property financing where the lender focuses on one thing: does the rental income from this property cover the mortgage payment? That's it. They calculate the Debt Service Coverage Ratio by dividing the property's monthly rental income by the monthly debt payment (including principal, interest, taxes, insurance, and HOA fees).

If that ratio hits 1.0 or higher, you're in business. The property pays for itself. Many lenders prefer to see a DSCR of 1.25, meaning the property generates 25% more income than the debt payment, but requirements vary.

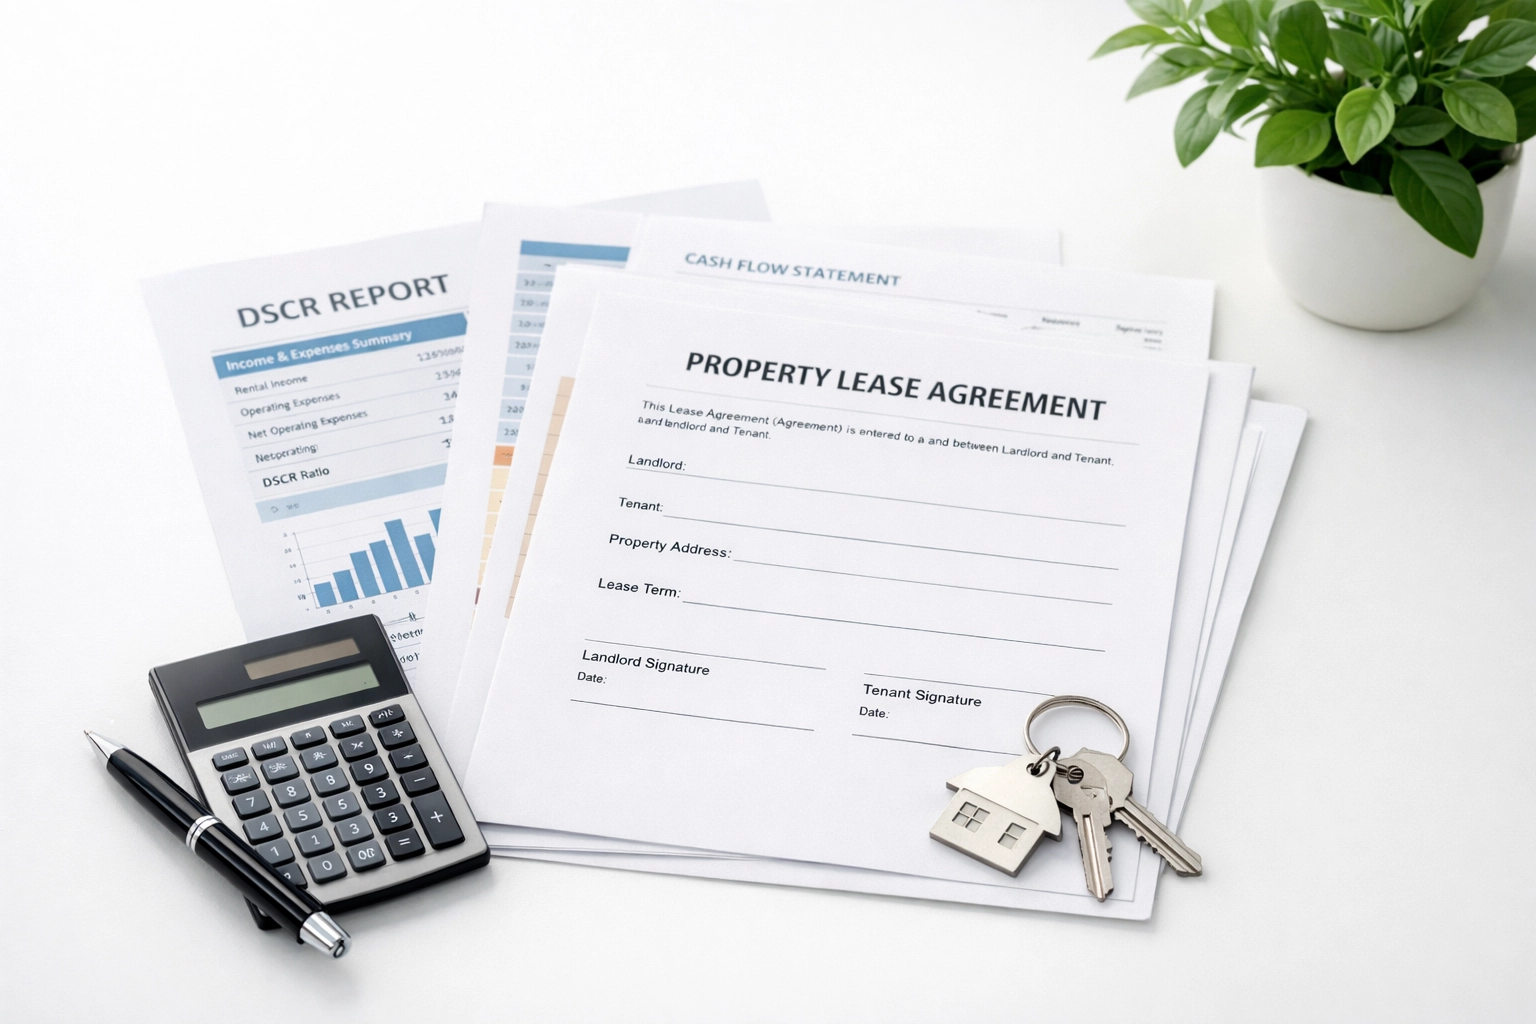
Calculator and rental property documents showing DSCR loan qualification process

The revolutionary part? They don't ask for your tax returns, pay stubs, or employment verification. Your personal income is essentially irrelevant to the equation.

Why Traditional Financing Holds Investors Back

Here's where most investors get stuck. Conventional mortgage lenders have strict debt-to-income requirements, typically maxing out around 43% to 50%. So even if you own ten cash-flowing rental properties, those mortgage payments count against your DTI ratio. Eventually, you can't qualify for another loan, even though your portfolio is profitable and growing.

Self-employed investors face an even tougher battle. You might be making great money, but if you're writing off business expenses (like you should), your taxable income looks lower on paper. Traditional lenders see those tax returns and say no, even though your actual cash flow is strong.

This is where DSCR loans change everything.

The Power of Property-Based Qualification

With DSCR financing, your personal income doesn't enter the conversation. The property's rental income is the star of the show. This opens doors that traditional lending keeps locked:

You can have complicated tax returns. Self-employed? Multiple LLCs? Depreciation eating into your taxable income? None of that matters. The lender looks at the lease agreement and market rents, not your 1040.

Your existing portfolio doesn't work against you. In fact, having more properties can actually help, because experienced investors often get better rates. Your other mortgages don't count against a personal DTI calculation.

You keep business and personal finances separate. Many investors prefer to hold properties in LLCs for liability protection. DSCR loans work beautifully with LLC ownership, whereas conventional financing often requires personal guarantees and makes entity ownership difficult.

Multiple investment properties including single-family home, duplex, and apartment building

Scaling Your Portfolio Without Hitting the Wall

This is where DSCR loans become absolutely essential for growth-minded investors. Because each property is evaluated independently based on its own income, you can finance multiple properties simultaneously or in quick succession.

Think about that for a second. With conventional financing, you might max out at 4-10 financed properties depending on the lender. With DSCR loans, the limiting factor isn't some arbitrary number, it's whether each property's income supports its debt. If you're buying solid cash-flowing properties, you can keep growing.

Some investors use DSCR loans to finance several properties at once when they find a portfolio deal or multiple opportunities in the same market. Others appreciate the ability to close quickly on new deals without waiting for their personal income documentation to be updated or verified.

Real-world scenario: You're a full-time investor who flipped properties last year but took most of your profit as a distribution that doesn't show up as W-2 income. Your tax return shows $50,000 in income, but you made $250,000. A traditional lender qualifies you based on that $50,000. A DSCR lender doesn't care about either number, they just want to know if the new property's rent covers the mortgage.

Speed and Simplicity in Underwriting

Let's talk about the practical benefits you'll experience when using DSCR financing.

Faster closings. Without needing to verify employment, request tax transcripts from the IRS, or document every deposit in your bank account, underwriting moves significantly faster. Many DSCR loans close in 3-4 weeks.

Less documentation stress. You'll need basic docs, property information, rent roll or lease agreement, down payment verification, but you won't be scrambling to explain that random $5,000 deposit from three months ago or providing letters of explanation for every little thing.

Flexibility in loan structure. DSCR lenders often offer interest-only payment options, 40-year amortizations, and other creative structures that improve cash flow. This flexibility lets you tailor the financing to your specific investment strategy.

Real estate portfolio growth pathway showing property investment scaling strategy

The Emerald Capital Funding Advantage

At Emerald Capital Funding, we've structured hundreds of DSCR loans for investors who are serious about building wealth through real estate. We understand that your portfolio's performance tells a better story than your tax returns ever could.

Our team specializes in creative financing solutions that work for real investors in real situations. Whether you're acquiring your third property or your thirtieth, we focus on getting you funded quickly so you don't miss opportunities in competitive markets.

We work with experienced investors who understand the fundamentals, buy in good markets, run the numbers conservatively, and maintain proper cash reserves. If that sounds like you, we want to be your financing partner.

Common DSCR Loan Applications

DSCR financing works for various property types and investment strategies:

  • Long-term rentals – Single-family homes, condos, or small multi-family properties (2-4 units) with traditional annual leases
  • Short-term rentals – Airbnb or VRBO properties where you can document income through tax returns or rental management reports
  • Multi-family properties – Larger apartment buildings where the combined unit income supports the debt
  • Portfolio acquisitions – Financing multiple properties at once when buying from another investor

The key is demonstrating reliable rental income through leases, market rent analysis, or historical income documentation.

Managing the Risks

No financing tool is perfect, and DSCR loans do come with considerations. Interest rates are typically 0.5% to 1.5% higher than conventional investment property loans because of the flexible qualification. You'll also need larger down payments, usually 20% to 25% minimum.

The bigger risk is over-leveraging. Just because you can finance a property based on its income doesn't always mean you should. Smart investors maintain cash reserves for vacancies, repairs, and market downturns. The property might support the debt payment when occupied, but what about when it's vacant for two months?

Run conservative numbers. Build in vacancy assumptions. Maintain reserves. If you're doing those things, DSCR financing becomes a powerful scaling tool rather than a risky overleveraging trap.

Organized DSCR loan documents and rental lease agreement on desk

Frequently Asked Questions

Q: What credit score do I need for a DSCR loan?

A: Most lenders require a minimum credit score of 660-680, though rates improve significantly at 720 and above. Some specialty programs go as low as 620 for experienced investors.

Q: Can I use a DSCR loan on my first investment property?

A: Yes, though some lenders prefer you have at least one other financed property. First-time investors can absolutely use DSCR financing: you'll just need to demonstrate the property's income potential clearly.

Q: What DSCR ratio do I need?

A: Most lenders want to see 1.0 or higher, with 1.25 being ideal. Some programs will go down to 0.75 DSCR if you're putting more money down or have strong reserves.

Q: How long does the rental history need to be?

A: If the property is already rented, the current lease works. For vacant properties, lenders use a market rent analysis (often an appraisal with rent schedule) to determine income.

Q: Can I refinance into a DSCR loan?

A: Absolutely. Many investors refinance conventional loans or even hard money loans into DSCR financing once the property is stabilized and producing income.

Ready to Scale Your Portfolio?

If you've been feeling stuck at your conventional lending limit, or if you're tired of explaining your tax strategy to underwriters who don't understand real estate investing, it's time to add DSCR financing to your toolbox.

The investors who build substantial portfolios understand this: the right financing strategy matters just as much as the right properties. DSCR loans remove the artificial barriers that traditional lending creates and let you grow based on what matters: property performance.

At Emerald Capital Funding, we're ready to discuss your portfolio goals and show you how DSCR financing can accelerate your growth. Whether you're looking to acquire your next property or refinance existing deals for better terms, we've structured these loans for investors just like you.

Ready to explore DSCR financing? Let's talk about your portfolio and find the right solution to keep you moving forward. The opportunities don't wait, and neither should you.